
De Cbw is de Nederlandse uitwerking van een Europese richtlijn (NIS2) en vervangt de bestaande Wet beveiliging netwerk- en informatiesystemen. Het doel is simpel: organisaties die belangrijk zijn voor de samenleving moeten hun digitale beveiliging op orde hebben. Een cyberincident bij hen kan namelijk grote gevolgen hebben voor anderen. Denk aan uitval van energie, zorg of digitale dienstverlening. Vanaf 15 augustus 2026 gelden er nieuwe verplichtingen voor ruim 8.000 organisaties in Nederland.
Deze aanpak is er niet zomaar gekomen. Onze economie en samenleving zijn steeds afhankelijker van digitale systemen. Die systemen zijn vaak ook met elkaar verweven. Een storing of hack bij een organisatie kan zich zo razendsnel verspreiden naar klanten, leveranciers en ketenpartners.
De Cbw geldt voor organisaties in 18 aangewezen sectoren, zoals energie, digitale infrastructuur, gezondheidszorg, vervoer, drinkwater en overheid. Ook sectoren die dichter bij het mkb liggen vallen eronder, denk aan afvalwaterbeheer, voedselproductie en -distributie, de maakindustrie voor bepaalde producten, en post- en koeriersdiensten. De volledige lijst met sectoren en de bijbehorende soorten organisaties vind je op de website van de NCTV.
Val je onder één van de aangewezen sectoren en heb je 50 of meer medewerkers, of een jaaromzet en een balanstotaal van beide meer dan 10 miljoen euro, dan kwalificeert je organisatie als belangrijke entiteit. Heb je 250 of meer medewerkers, of een jaaromzet van meer dan 50 miljoen euro en een balanstotaal van meer dan 43 miljoen euro, dan word je aangemerkt als essentiële entiteit.
Het verschil zit vooral in het toezicht. Als essentiële entiteit controleert de toezichthouder actief of je aan de wet voldoet, ook zonder aanleiding. Bij een belangrijke entiteit wordt daarentegen meestal pas gecontroleerd na een concreet signaal of incident.
Let op! Ook als je organisatie op het eerste gezicht niet in een van deze sectoren lijkt te vallen, of klein van omvang is, kan de Cbw toch van toepassing zijn. De minister kan een organisatie namelijk alsnog aanwijzen als essentiële of belangrijke entiteit. Dit kan ook als de organisatie niet aan de gebruikelijke voorwaarden voldoet, bijvoorbeeld omdat zij een grote maatschappelijke impact kan hebben bij uitval. Ga er dus niet te snel vanuit dat de wet je niet raakt.
Tip! Wil je snel weten of jouw organisatie onder de Cbw valt? Met deze zelfevaluatie kan je dat nagaan.
Val je onder de Cbw, dan krijg je te maken met:
Ook wordt de verantwoordelijkheid voor cyberbeveiliging expliciet bij je bestuur gelegd. Je bestuur moet de genomen maatregelen goedkeuren en er toezicht op houden. Onderdeel hiervan is de plicht om bestuursleden hierin op te leiden, zodat zij cyberrisico's kunnen herkennen en beoordelen.
Val je niet onder de Cbw, dan is dit ook een goed moment om je beveiliging eens tegen het licht te houden. Werk je voor of met organisaties die wel onder de wet vallen, dan is de kans groot dat zij ook van jou passende beveiligingsmaatregelen gaan verwachten, simpelweg omdat jij onderdeel bent van hun keten.
Let op! Alle informatie over de Cbw staat op de website van het NCSC. Heb je meer, of specifieke, vragen over de Cbw en wat dit concreet voor je betekent? Neem contact met ons op, we denken graag met je mee.
Vroeger was het in de informatiebeveiliging vooral zaak om beter beveiligd te zijn dan je buurman, zodat aanvallers eerder bij hem aanklopten en niet bij jou. Die tijd is voorbij. De gehele samenleving moet weerbaarder worden tegen cyberdreigingen. Iedereen die daarin een belangrijke rol speelt moet eraan meewerken. Daarom is er vanaf 15 augustus 2026 de Cyberbeveiligingswet (Cbw). Valt jouw bedrijf daar ook onder? Hieronder lees je in het kort waar je aan toe bent.
LEES VERDER
Uit onderzoek is gebleken dat de onjuiste uitkeringen onder meer veroorzaakt werden door een foute vaststelling van het dagloon in de periode 1 januari 2020 en 31 december 2024.
Een andere oorzaak is gelegen in het niet indexeren van het dagloon tussen 1 juli 2006 en 31 december 2022.
Tenslotte wordt ook compensatie geboden naar aanleiding van een uitspraak van de Centrale Raad van Beroep voor WIA-uitkeringen waarvan het recht inging op of na 1 juli 2015 met een uiterste datum van dagloonvaststelling op 4 augustus 2025. Deze uitspraak betrof de vaststelling van het dagloon in situaties waarin een werknemer in de WIA-referteperiode (= het jaar voordat iemand ziek werd) in een kalendermaand geen inkomen heeft genoten.
Uitkeringsgerechtigden die te weinig uitkering hebben gekregen, ontvangen een eenmalige netto vergoeding. Hierover hoeft geen loon- en inkomstenbelasting betaald te worden en de uitkering telt ook niet mee voor het verzamelinkomen. Dit betekent dat de uitkering geen invloed heeft op inkomensafhankelijke uitkeringen, zoals huur- of zorgtoeslag.
Vanaf deze zomer horen de eerste uitkeringsgerechtigden of hun uitkering te hoog is, te laag, of gelijk blijft. Een te lage uitkering wordt direct aangepast, een te hoge pas na twee maanden. Degenen met een te lage uitkering horen ook welke eenmalige vergoeding zij ontvangen. Vanaf oktober 2026 worden de eerste vergoedingen uitbetaald.
Let op! Als blijkt dat de WIA-uitkering te hoog is vastgesteld, dan wordt het te veel ontvangen bedrag niet teruggevorderd.
Uitkeringsgerechtigden worden door het UWV op de hoogte gehouden het verloop van de gang van zaken met betrekking tot de eenmalig netto vergoeding. Een wijziging van het dagloon wordt ook doorgegeven aan een eventuele pensioenuitvoerder. Bij eventuele vragen biedt het UWV onafhankelijk financieel advies.
Let op! UWV start deze zomer met de hersteloperatie, maar deze duurt waarschijnlijk tot eind 2027. Het kan dus nog even duren voordat je bericht krijgt van UWV.
Door gemaakte fouten bij het UWV heeft een aantal uitkeringsgerechtigden de afgelopen jaren een onjuiste WIA-uitkering (Wet werk en inkomen naar arbeidsvermogen) ontvangen. Zij worden hiervoor vanaf dit najaar gecompenseerd via een eenmalige uitkering. Minister Vijlbrief heeft de betreffende vergoedingsregeling bekendgemaakt.
LEES VERDER
Het gemiddelde premieniveau van de WGA bedraagt in 2027 1,07% (2026: 0,96%). De maximum WGA-premie is 4,28% en de minimumpremie 0,26% (in 2026: 3,84 respectievelijk 0,24%).
De gemiddelde premie voor de ZW bedraagt in 2027 0,60% (2026: 0,56%). De maximum ZW premie is 2,40% en de minimumpremie 0,15% (in 2026:2,24% respectievelijk 0,14%).
Let op! Voor werkgevers in sector 52 (Uitzendbedrijven) geldt een afwijkende maximumpremie van 5,96%.
De gedifferentieerde premie Whk is afhankelijk van de grootte van je onderneming. Bij middelgrote en grote werkgevers telt de eigen instroom van zieken in het publieke stelsel mee voor de hoogte van de premie.
De loonsom over 2025 bepaalt in welke categorie je in 2027 valt. De basis hiervoor is het gemiddelde premieplichtig loon. Dit bedraagt in 2026 nog € 43.300 en stijgt in 2027 naar € 45.400.
De grens tussen kleine en middelgrote werkgevers ligt in 2027 bij een loonsom van maximaal € 1.135.000 (in 2026 € 1.082.500). Bij een loonsom van meer dan € 4.540.000 is in 2027 sprake van een grote werkgever (in 2026 € 4.330.000).
Let op! Alle grote en middelgrote werkgevers ontvangen tegen het einde van 2026 een beschikking van de Belastingdienst met de hoogte van de premie. Kleine werkgevers ontvangen geen beschikking, maar een mededeling.
Ben je eigenrisicodrager, maar wil je dat niet meer zijn vanaf 1 januari 2027? Meld je dan vóór 1 oktober 2026 af. Ben je geen eigenrisicodrager, dan kun je dat worden vanaf 1 januari 2027 door je vóór 1 oktober 2026 aan te melden. Je betaalt dan niet langer de premies WGA en ZW.
Let op! Of het zinvol is om te wisselen is van diverse omstandigheden afhankelijk. Denk aan (de wijziging van) de instroom van zieken in het publieke stelsel, hoeveel zieken buiten het publieke stelsel zitten bij terugkeer naar dit stelsel en de kosten van een private verzekering etcetera. Overleg daarom met onze adviseur of wisselen raadzaam is. Aan- of aanmelden kan voor de WGA vervolgens met dit formulier en voor de ZW met dit formulier.
De gedifferentieerde premies Werkhervattingskas (Whk) voor 2027 zijn bekend. De premies Werkhervatting gedeeltelijk arbeidsgeschikten (WGA) en Ziektewet (ZW), die onderdeel hiervan zijn, gaan in 2027 beiden omhoog.
LEES VERDER
Bij de koop van een woning is de koper in beginsel overdrachtsbelasting verschuldigd. Het normale tarief bij verkrijging van een woning bedraagt op dit moment 8%. Wordt de woning door de koper na aankoop anders dan tijdelijk als hoofdverblijf gebruikt, dan geldt een tarief van 2%. Er bestaat dan ook een eenmalige startersvrijstelling voor kopers die minstens 18 jaar oud zijn en jonger zijn dan 35 jaar, als de woning een maximale waarde heeft van €555.000 (cijfer 2026).
In een rechtszaak bij gerechtshof Amsterdam had een echtpaar een woning gekocht, deze vervolgens helemaal laten slopen (inclusief de fundering) en op dezelfde plaats een nieuwe woning laten bouwen. Het echtpaar had geen overdrachtsbelasting afgedragen, ervan uitgaande dat er recht bestond op de startersvrijstelling. De Belastingdienst was het hiermee niet eens en had een naheffingsaanslag opgelegd naar het normale tarief.
Bij het tot stand komen van het lage tarief en de vrijstelling overdrachtsbelasting is bepaald dat deze ook gelden voor de verkrijging van een nieuwe woning in aanbouw. Van dit laatste is sprake vanaf het moment dat de fundering van een woning is aangebracht.
Het gerechtshof kwam in het geval van het echtpaar tot de conclusie dat er geen recht bestond op de startersvrijstelling, omdat de verkochte woning volledig gesloopt was, inclusief fundering. De oude woning was volledig opgehouden te bestaan en kon dus niet meer worden bewoond. Daarom werd niet voldaan aan de eis dat de verkregen woning anders dan tijdelijk als hoofdverblijf gebruikt zou gaan worden.
Als de fundering niet was gesloopt, had dit in deze casus verschil gemaakt. De Belastingdienst had namelijk bij de rechtbank verklaard dat wel aan het hoofdverblijfcriterium was voldaan als de fundering was gebleven en gebruikt was voor de nieuwe woning.
Het echtpaar vond hun situatie vergelijkbaar met situaties waarin de fundering wel behouden was, maar het gerechtshof ging daar niet in mee. De Hoge Raad heeft eerder namelijk beslist dat er voor de overdrachtsbelasting geen sprake is van discriminatie als bouwgrond mét fundering wel als een woning wordt aangemerkt en bouwgrond zonder fundering niet. Het echtpaar deed dan ook tevergeefs een beroep op het gelijkheidsbeginsel om alsnog de startersvrijstelling te kunnen claimen.
Let op! Het is niet helemaal duidelijk of het funderingscriterium ook betrekking heeft op sloopwoningen. Het gerechtshof geeft in de uitspraak aan dat uit de wetsgeschiedenis zou kunnen worden afgeleid dat dit criterium alleen geldt voor woningen in aanbouw. In dat geval is de verklaring van de Belastingdienst bij de rechtbank begunstigend beleid geweest, waarvan het niet helemaal duidelijk is of dit door de Belastingdienst breed gedragen wordt. Overleg over uw eigen situatie daarom altijd met onze adviseurs.
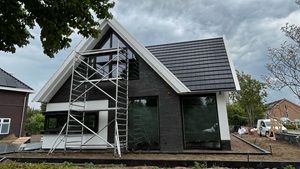
Wie een woning koopt, deze laat slopen en vervolgens op de grond een nieuwe woning laat bouwen, loopt het risico dat het normale tarief overdrachtsbelasting verschuldigd is. Dit was aan de orde in een uitspraak van gerechtshof Amsterdam. Wat speelde hier?
LEES VERDER
De MKB Klimaatwijzer geeft je informatie over maatregelen en subsidies die bij je ondernemingen passen. Bijvoorbeeld over zonnepanelen, elektrisch bedrijfswagens en maatregelen waarmee je energie kunt besparen.
De MKB Klimaatwijzer is een interactieve tool. Je vult maximaal 10 minuten een aantal vragen in en krijgt daarna een persoonlijk overzicht. Je kunt aan het begin van de vragenlijst aangeven over welke onderwerpen je advies wilt: energiebesparing, vervoer, innovatie of provinciale regelingen.
Het ministerie van Klimaat en Groene Groei heeft in samenwerking met de Rijksdienst voor Ondernemend Nederland (RVO) de MKB Klimaatwijzer ontwikkeld. Met behulp hiervan kun je een overzicht krijgen van maatregelen, subsidies en andere mogelijkheden om energie te besparen en je onderneming te verduurzamen.
LEES VERDER
Wettelijk is vastgelegd dat belastingplichtigen recht hebben op inzage in hun eigen fiscale dossier bij de Belastingdienst. In de brief geeft de staatssecretaris aan hoe de implementatie van dit fiscaal inzagerecht de komende jaren gestalte gaat krijgen, wat het beoogde tijdpad is en welke uitzonderingen er op het inzagerecht gemaakt gaan worden.
Op dit moment is bij de Belastingdienst nog geen centrale dossiervorming: de informatie van het fiscale dossier is nog vergaand versnipperd in tientallen niet aan elkaar gekoppelde systemen. Voor het fiscale inzagerecht zal de Belastingdienst daarom een verandering in de manier van werken door moeten voeren. Het doel is het bereiken van een gestructureerde, extern gerichte en ontsluitbare dossiervorming, aldus de staatssecretaris. De stukken van het fiscaal dossier zullen de komende jaren stapsgewijs digitaal beschikbaar gesteld worden.
Met het op dit moment binnen de Belastingdienst uitgevoerde programma ‘Keuze digitaal’ zullen beschikkingen, uitnodigingen, herinneringen en ingediende stukken tot 2030 stapsgewijs beschikbaar komen in MijnBelastingdienst (Zakelijk). Dit wordt later uitgebreid met standaardbrieven en automatische berichten, gevolgd door informatie uit individuele dossiers bijvoorbeeld over de behandeling van een aangifte.
In de brief staat ook een voorlopig tijdpad, waarin de voorgenomen invoering van het fiscale inzagerecht is opgenomen:
Voor de Douane zou het fiscale inzagerecht alleen van toepassing zijn op accijnzen en verbruiksbelastingen. De staatssecretaris zondigt deze heffingen echter uit van het fiscale inzagerecht. Dit laatste betekent niet dat de Douane zich niet inzet op het verder verbeteren van de informatiepositie en rechtsbescherming van belastingplichtigen, zo geeft de bewindsman aan.
De staatssecretaris van Financiën heeft in een brief aan de Tweede Kamer de stand van zaken geschetst met betrekking tot de invoering van het fiscale inzagerecht. Invoering van dit fiscaal inzagerecht zal in fases gebeuren.
LEES VERDER
De SEM kan aangevraagd worden door melkveehouders die melk- en kalfkoeien houden voor de productie van melk. Zij hebben hiervoor een verklaring nodig dat hun bedrijf binnen het mkb valt.
Met de subsidie kunnen melkveehouders de uitstoot van ammoniak en broeikasgassen en de productie van mest verlagen. Hiermee wordt ook de uitstoot van stikstof verminderd.
Melkveehouders die een beroep doen op de SEM moeten 10% tot 20% minder koeien gaan houden ten opzichte van 2025. Het verlies aan inkomen als gevolg van de verminderde melkopbrengst wordt dan drie jaar lang door de SEM gecompenseerd.
De melkveehouder ontvangt ook een vergoeding voor het vervallen van het fosfaatrecht dat samenhangt met de vermindering van het aantal koeien.
Let op! De ingeleverde fosfaatrechten verdwijnen definitief van de markt.
Naast de vermindering van het aantal koeien met 10% tot 20% mag het areaal grasland van de subsidievrager drie jaar lang niet afnemen. Ook mag het aantal graasdieren (jongvee, schapen, geiten, paarden enzovoort) gedurende die periode niet toenemen.
Let op! Lees de exacte voorwaarden op de website van RVO.
De subsidie voor het verlies aan melkinkomsten bedraagt € 1.606 per verminderde koe. Dit is gebaseerd op de melkproductie van een gemiddelde koe, inclusief transactiekosten. De vergoeding voor het inleveren van een fosfaatrecht bedraagt € 110 per recht. Deze vergoeding wordt in drie jaarlijkse termijnen uitbetaald.
Let op! De maximale subsidie bedraagt € 400.000.
Aanvragen van de SEM kan bij RVO tot en met 27 januari 2026 17.00 uur. Op 22 juli 2026 hadden 42 melkveehouders zich aangemeld voor de SEM. Het totale budget voor de SEM bedraagt. € 615.700.000.
Tip! Op de website van RVO is een rekentool opgenomen waarmee je een schatting van de subsidie kunt maken.
Deelnemers aan de SEM kunnen na de periode van drie jaar eventueel terugkeren naar het oorspronkelijke aantal koeien. Wel zullen ze dan nieuwe fosfaatrechten aan moeten schaffen.
Tip! Nederlandse banken verlenen een rentekorting aan melkveehouders die via deelname aan de Sem tijdelijk gaan extensiveren en overgaan tot nieuwe duurzame investeringen.
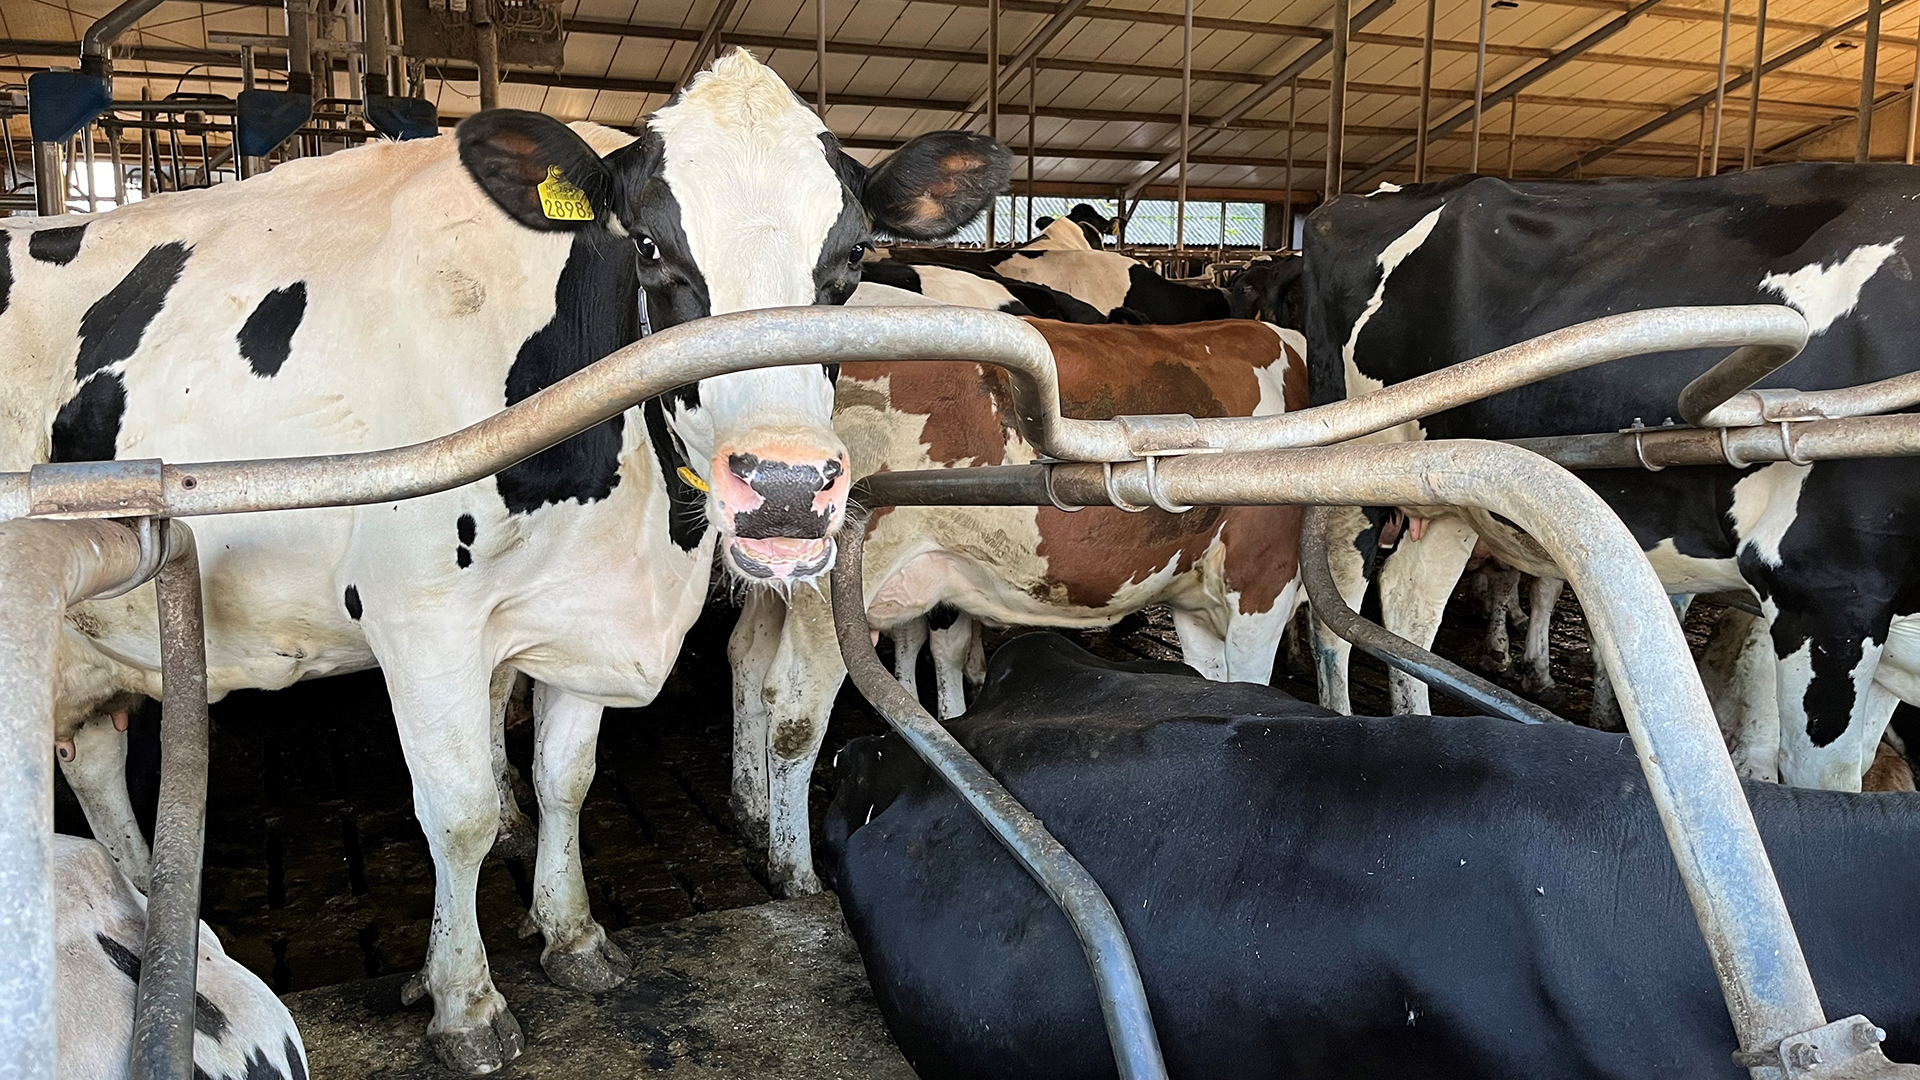
De Subsidieregeling extensivering melkveehouderij (SEM) zou oorspronkelijk openstaan van 1 juni tot en met 29 juli 2026. De openstelling is echter verlengd tot en met 27 januari 2027 17.00 uur.
LEES VERDER
Op 25 juni 2026 besliste de Hoge Raad al dat niet-bezwaarmakers geen recht hebben op rechtsherstel box 3 voor de jaren 2017-2020. In de collectieve beslissing komt de Belastingdienst tot dezelfde conclusie.
De Hoge Raad oordeelde op 24 december 2021 in het kerstarrest dat de forfaitaire box 3-heffing vanaf 2017 in strijd is met het Europees recht. De Hoge Raad bood in die casus rechtsherstel door aan te sluiten bij het werkelijke rendement. Daarna kreeg elke belastingplichtige van wie de aanslag inkomstenbelasting (hierna: IB) op 24 december 2021 nog niet onherroepelijk vaststond, rechtsherstel volgens een in juli 2022 ingevoerde Herstelwet.
Dit gold niet voor belastingplichtigen van wie de aanslag IB op 24 december 2021 wel al onherroepelijk vaststond. Voor deze belastingplichtigen, de zogenaamde niet-bezwaarmakers, werd de massaalbezwaarplusprocedure (MB+-procedure) ingevoerd.
In de MB+-procedure stond de vraag centraal of mensen die niet of te laat bezwaar maakten tegen box 3, toch hun box 3-inkomen over de jaren 2017 tot en met 2020 mogen berekenen op basis van werkelijk rendement.
De Hoge Raad oordeelde in mei 2022 al dat deze mensen dat niet mogen, omdat zij niet of te laat bezwaar indienden. De koepel- en belangenorganisaties (Bond voor Belastingbetalers, Consumentenbond, NOB, RB en SRA) meenden dat in de uitspraak van de Hoge Raad nog niet met alles rekening was gehouden. Daar ging de MB+-procedure over.
De Hoge Raad sprak op 25 juni 2026 uit geen reden te zien om terug te komen op de uitspraak van mei 2022, ook niet op basis van de argumenten die eerder nog niet aan de orde waren gekomen. Dit betekent dat de Hoge Raad bij zijn standpunt is gebleven dat niet-bezwaarmakers geen recht op teruggaaf van box 3 over de jaren 2017 tot en met 2020 hebben.
Op 17 juli 2026 heeft de Belastingdienst, in overeenstemming met het oordeel van de Hoge Raad, alle verzoeken in de MB+-procedure afgewezen en alle bezwaren ongegrond verklaard.
Let op! Tegen deze collectieve beslissing kan geen beroep in worden gesteld.
Stonden ook jouw aanslagen IB 2017-2020 op 24 december 2021 onherroepelijk vast en diende je daarna een verzoek om ambtshalve vermindering in? Dan zijn deze verzoeken onderdeel van de MB+-procedure. Deze verzoeken zijn door de Belastingdienst met de collectieve beslissing van 17 juli 2026 afgewezen. Je krijgt daarom definitief geen teruggaaf box 3 over deze jaren.
Dit betekent ook dat je voor de jaren geen beroep kunt doen op de uitspraak van de Hoge Raad van 6 juni 2024. In dit zogenaamde D-day-arrest bepaalde de Hoge Raad dat de Herstelwet naar aanleiding van het Kerstarrest ook niet door de beugel kon. Sindsdien wordt rechtsherstel toegepast volgens de door de Hoge Raad geformuleerde uitgangspunten van het werkelijke rendement. Als deze MB+-procedure positief was afgelopen, hadden de niet-bezwaarmakers ook hierop een beroep kunnen doen. Dat is nu dus ook definitief van de baan.
De Belastingdienst heeft op 17 juli 2026 de verzoeken om ambtshalve vermindering van niet-bezwaarmakers betreffende box 3 voor de jaren 2017-2020 in een collectieve beslissing definitief afgewezen. Wat betekent dit en wat ging hieraan vooraf?
LEES VERDER
Eind 2024 is al in de wet opgenomen dat de eerste schijf in de vrije ruimte van de werkkostenregeling (WKR) per 1 januari 2027 omhooggaat van 2 naar 2,16%. SEO Economisch Onderzoek (SEO) heeft, na een evaluatie van de WKR over de jaren 2019-2024, echter aanbevolen om de eerste schijf in de vrije ruimte helemaal af te schaffen. Op Prinsjesdag 2026 wordt waarschijnlijk duidelijk of het kabinet deze aanbeveling overneemt.
Ook wordt dan duidelijk of het kabinet de volgende aanbevelingen van SEO overneemt:
De verwachting is dat in ieder geval de gerichte vrijstelling voor kortingen en vergoedingen voor producten uit eigen bedrijf wordt afgeschaft.
Het vergoedingspercentage in de expatregeling (voorheen: 30%-regeling) gaat per 1 januari 2027 omlaag van 30 naar 27%. Tegelijkertijd gaan er ook hogere salarisnormen gelden. Deze aanpassingen zijn al eerder in de wet opgenomen. Het kabinet heeft aangegeven niet van plan te zijn de expatregeling nog verder te versoberen.
Al eerder bekendgemaakt – en ook al in werking getreden met terugwerkende kracht vanaf 1 januari 2026 –, is de verhoging van het belastingvrije bedrag voor reiskosten van € 0,23 naar € 0,25. Deze verhoging geldt voor de onbelaste reiskostenvergoeding die een werkgever aan zijn werknemer geeft, en voor de aftrekbare zakelijke reiskosten van een ondernemer of resultaatgenieter in de inkomstenbelasting. Je mag vanaf de aangifte IB 2026 ook rekening houden met dit hogere bedrag bij het berekenen van de aftrekbare ziektekosten.
Let op!De verhoging naar € 0,25 is nu nog in een besluit opgenomen, maar wordt in het belastingpakket van Prinsjesdag 2026 ook in de wet opgenomen.
Een werkgever die een personenauto aan een werknemer ter beschikking stelt, ofwel een auto van de zaak, moet vanaf 2027 een pseudo-eindheffing aan de Belastingdienst betalen van 12% over de cataloguswaarde van de personenauto, inclusief btw en bpm. Dit voorstel is vorig jaar al aangenomen, maar op Prinsjesdag 2026 worden aanpassingen verwacht, zoals een uitzondering op de pseudo-eindheffing voor vervangende auto’s bij schade, reparatie en onderhoud, en een uitzondering op de heffing voor lesauto’s.
Het kabinet denkt erover om de leeftijdsgrens in de youngtimerregeling niet ineens per 1 januari 2027 te verhogen van 16 naar 25 jaar. Een auto van de zaak die onder de youngtimerregeling valt, kent een bijtelling van 35% van de waarde in het economisch verkeer in plaats van de reguliere bijtelling die geldt voor jongere auto’s. Het kabinet denkt nog na over een ander afbouwpad in plaats van de verhoging naar 25 jaar per 1 januari 2027.
Het kabinet heeft de gedachte om een nieuwe bijtellingskorting te introduceren voor elektrische auto’s tussen de vijf en acht jaar oud. Deze regeling zou de naam Greentimerregeling moeten krijgen.
Er ligt een plan om een belastingkorting in de loonbelasting te introduceren voor voordelen uit aandelenopties voor werknemers van start-ups en scale-ups. De belastingkorting wordt vormgegeven door de grondslag van de voordelen uit aandelenopties te beperken tot 65%, zodat over een lager voordeel belasting wordt geheven. Het effectieve loonheffingentarief wordt dan afgerond 32%, waarmee het ongeveer gelijk is aan de belastingheffing over aandelenopties in box 2.
Het kabinet heeft eerder aangegeven het wetsvoorstel hiervoor in september 2026 aan de Tweede Kamer te willen aanbieden. Het streven is om de lagere loonheffing op aandelenopties per 1 januari 2027 in werking te laten treden.
Wat betreft aftrekmogelijkheden voor ondernemers worden de volgende wijzigingen in het belastingpakket verwacht:
Voor de particulier wordt waarschijnlijk de aftrek van specifieke zorgkosten afgeschaft per 1 januari 2028. Verder worden op Prinsjesdag diverse aanpassingen op het nog bij de Eerste Kamer in behandeling zijnde wetsvoorstel Werkelijk rendement box 3 verwacht. Hiervoor liggen verschillende opties, waarover het kabinet in augustus nog een besluit neemt.
Waarschijnlijk gaat het algemene woningtarief in de overdrachtsbelasting omlaag van 8 naar 7% per 1 januari 2027. Dit tarief geldt voor de verkrijging van woningen die de verkrijger niet zelf als hoofdverblijf gaat gebruiken.
Voor overdrachten van woningen tussen woningcorporaties binnen de sociale huisvestingstaak komt er waarschijnlijk een vrijstelling overdrachtsbelasting.
Het plan om per 1 januari 2028 het btw-tarief op sierteeltproducten te verhogen van 9 naar 21% btw wordt ook in de belastingpakketten op Prinsjesdag 2026 verwacht.
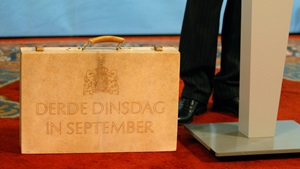
Op dinsdag 15 september 2026 is het weer Prinsjesdag. Een aantal plannen van het kabinet is al bekend. In dit artikel vind je een selectie van wat er op fiscaal gebied te verwachten is.
LEES VERDER
Bij maatschappelijk vastgoed moet je denken aan scholen, overheidsgebouwen, zorginstellingen, sportaccommodaties en monumenten. De subsidie DUMAVA is beschikbaar voor maatschappelijke instellingen in de sectoren decentrale overheid, onderwijs, zorg, cultuur en religieuze instellingen.
De subsidie kan verder aangevraagd worden door stichtingen en verenigingen voor gebouwen met een publieksfunctie. Ook eigenaren van een geregistreerd rijks-, provinciaal of gemeentelijk monument kunnen DUMAVA aanvragen. Hetzelfde geldt voor veiligheidsregio’s met maatschappelijk vastgoed.
Er gelden verschillende voorwaarden voor het aanvragen van de subsidie. Belangrijk is dat je eerst een verduurzamingsadvies laat opstellen voordat je DUMAVA aanvraagt. Verder dien je eerst DUMAVA aan te vragen en pas na toekenning van de subsidie een contract aan te gaan met een aannemer of te starten met de verduurzaming. Doe je dat niet, dan loop je het risico geen subsidie te krijgen.
Let op! Kijk voor alle voorwaarden hier.
DUMAVA is ook beschikbaar voor amateursportverenigingen, mits voor de sportaccommodatie niet al eerder BOSA-subsidie is ontvangen.
Let op! Voor amateurverenigingen gelden wel extra voorwaarden.
De hoogte van de subsidie is afhankelijk van het aantal verduurzamingsmaatregelen:
De aanvraagperiode startte op 1 juni 2026 9.00 uur en loopt tot en met vrijdag 16 oktober 2026 17.00 uur. Er is € 405 miljoen budget beschikbaar gesteld. Op 3 augustus 2026 was hier nog ruim 283 miljoen (70%) van over. Er is dus nog voldoende budget beschikbaar.
Voor het verduurzamen van maatschappelijk vastgoed is de subsidieregeling duurzaam maatschappelijk vastgoed (DUMAVA) beschikbaar. Begin augustus was nog 70% van het budget beschikbaar.
LEES VERDER
Please note! Not all the points listed below are taken from the 2027 Tax Plan. Some changes had already been decided upon, but adjustments have since been made to them.
From 2027, the government will be scaling back various tax benefits for entrepreneurs.
The entrepreneur’s allowance reduces the profit on which an entrepreneur pays income tax. From 2027, further cuts will apply to various components of this allowance.
Please note! This scheme applies to self-employed people who do not meet the 1,225-hour criterion but do meet the reduced 800-hour criterion and are entitled to incapacity benefit.
The cessation allowance and the rates for the co-worker allowance will cease to apply at the start of the third calendar year following the year in which the reduction takes effect. As the changes come into force in 2027, the schemes will therefore cease to apply on 1 January 2030.
As of 1 January 2028, another tax benefit for business owners will be abolished: the discretionary depreciation scheme for start-ups.
Start-up business owners, those planning to cease trading within a few years, and business owners with a co-working partner will be particularly affected. The choice between a sole trader, a general partnership (VOF) or a private limited company (BV) therefore once again requires a calculation based on actual profits and personal circumstances.
Please note!If there are significant changes to your profits, business partnerships or business succession, have a fresh assessment carried out to determine which legal form is best suited to your business.
Tip! Due to the higher aggregate income, benefits may also change. You should therefore check your estimated income for benefit purposes in good time for 2027 and 2028.
Employers may, with retroactive effect up to and including 1 January 2026, reimburse a maximum of €0.25 per business kilometre tax-free. This was previously €0.23. The increase also applies to commuting. The government is now enshrining this increase in law with retroactive effect.
Please note!The increase does not automatically mean that every employee is entitled to €0.25 per kilometre. This depends on the employment contract, the collective labour agreement and the employer’s own mobility policy. For employers, a higher allowance may lead to higher wage costs.
The discretionary allowance on the first €400,000 of the taxable wage bill will increase from 2% to 2.16% with effect from 1 January 2027. This will give you a maximum of €640 extra discretionary allowance per year. This increase was adopted earlier and is therefore not part of the 2027 Tax Plan.
Tip! Update your staff handbook, expense claim policy and payroll administration in good time, and assess whether a higher mileage allowance is desirable from both a financial and employment conditions perspective. Does your organisation offer staff discounts on sector-specific products? If so, consider what the end of this exemption will mean. This will mainly affect the retail and manufacturing sectors.
If, as an employer, you make a passenger car with emissions available to an employee for private use from 2027 onwards, you will be subject to a pseudo-final levy of 12 per cent of the list price. This levy is in addition to the employee’s additional tax liability and must not be passed on to the employee. Transitional provisions apply to cars made available before 1 January 2027.
The pseudo-final levy was already adopted last year, but following consultation, four amendments are being proposed.
The ‘youngtimer’ scheme will be scaled back more gradually than previously stipulated, and the changes will be less far-reaching. The additional tax liability will continue to be based on the market value, but the age limit will rise from 16 years to 17 years in 2027 and to 20 years from 2028 onwards. The previously planned rapid increase to 25 years from 2027 will therefore not go ahead.
Transitional provisions apply to cars that have already been made available by 31 December 2025 at the latest and which will be 17 years old in 2027. These cars may continue to benefit from the youngtimer scheme throughout 2027. From 1 January 2028, the scheme will only apply to cars older than 20 years.
For employers, the decision to provide a company car is becoming increasingly important, particularly due to the ‘pseudo-final levy’. The contract term, drive type and the date on which a car is first made available can have significant tax implications. As a result, an existing lease plan may turn out to be much more expensive or, conversely, much more attractive.
Tip! Before making any new leasing decisions, carefully assess the total employer costs, the employee’s additional tax liability, the lease term and the transitional tax rules.
Normally, the thresholds for tax bands and various tax credits in Box 1 rise in line with inflation. This means that the tax burden normally remains the same as income rises, in line with inflation.
In 2027 and 2028, the government will apply the inflation adjustment only partially. Without this measure, the inflation adjustment for 2027 would amount to 2.6 per cent. Of this, 48 per cent will be applied. As a result, tax band thresholds and tax credits will rise less in line with inflation. Incidentally, the 48 per cent is not applied to the second tax bracket threshold, which therefore remains the same in 2027 as in 2026. The first tax bracket threshold rises from €38,883 to €39,247. The second tax bracket threshold remains at €78,426.
At the same time, the Box 1 rates are changing. For taxpayers under the state pension age, the rate in the first tax bracket will rise by 0.48 per cent: from 35.75 per cent in 2026 to 36.23 per cent in 2027. The rate in the second tax bracket will rise by 0.60 per cent: from 37.56 per cent to 38.16 per cent. The rate in the third tax bracket remains at 49.50 per cent.
Due to the increase in rates and limited indexation, the tax burden in Box 1 will rise. This effect is mitigated for homeowners who can also deduct their mortgage interest at the higher rate of up to 38.16%.
Please note! Always assess your salary, dividends and profits in conjunction with one another. The tax burden may in fact be unexpectedly higher, as the general tax credit depends on your aggregate income. This may therefore also fall as a result of a dividend payment.
Box 3 taxes private assets, such as savings, investments and a second home. Under the current system, the tax authorities calculate the return largely using flat-rate figures. If your actual return is lower, you can provide evidence to the contrary, subject to certain conditions.
The Government has provisionally deferred consideration of the ‘Actual Return on Box 3’ Bill. It will present a new proposal in the 2027 Spring Memorandum. Consequently, the intended introduction on 1 January 2028 will not take place, or at the very least, this date remains uncertain. The Government is re-examining whether a capital gains tax would be more appropriate than a capital appreciation tax.
Under a capital appreciation tax, even an unrealised increase in value is taken into account annually. Under a capital gains tax, tax is only levied upon, for example, the sale of an asset. For entrepreneurs and directors/major shareholders with investments, let property or other assets that are difficult to sell, this makes a significant difference.
Please note!Until a new system comes into force, it remains important to keep accurate records of interest, dividends, rent, costs and changes in value. This information is required for the rebuttal scheme and for weighing up whether to invest privately or through a private limited company.
Tip! Do not wait for the new system. Record the actual return on each asset annually and retain the supporting documents.
The government is making various tax schemes for investment and innovation more attractive. For example, the energy investment allowance will rise from 40% to 45.5% with effect from 1 January 2027. Are you investing in qualifying energy-efficient business assets? If so, you’ll be able to deduct a larger portion of your investment from your profits.
The tax relief for research and development work is also being extended. The flat-rate hourly wage will rise from €29 to €33. This scheme reduces the payroll tax you, as an employer, pay when your employees are working on technically new products, processes or software.
Does your business make use of the innovation box? This scheme is also being made more attractive. From 1 January 2027, the maximum flat-rate amount will rise from €25,000 to €100,000 per year. The flat rate remains capped at 25% of profit. The current three-year application period will also remain unchanged. This allows you to have a larger proportion of your profit taxed at the lower Innovation Box rate.
Tip! Do you wish to make use of the energy investment allowance? Before entering into any commitments, check whether the business asset is included on the energy list. Then submit your application to RVO within the applicable three-month deadline.
To stimulate innovation and growth in specific young enterprises, the government is introducing an attractive tax scheme for employee share options at start-ups and scale-ups.
In principle, the employee pays tax when they actually sell the shares acquired through the options. After deducting the exercise price attributable to the shares, only 65 per cent of the benefit is taxed as income, subject to certain conditions. If the employee sells the share option right rather than the shares themselves, this lower tax base does not apply. The employee may also opt in writing for earlier taxation at the time the option right is exercised or as soon as the shares become tradable.
The scheme applies only to companies that qualify as start-ups or scale-ups and hold a decision from RVO. This decision is valid for eight years from the date of issue. Subject to certain conditions, you may extend the decision in five-year increments, up to a maximum total duration of 23 years. In addition, in principle, there must be a minimum period of two years between the grant of the share option and the sale of that option or the shares resulting from it. If the employee sells earlier due to a sale following the company’s initial public offering (IPO), an exception applies and the rule does apply.
The scheme is due to come into force on 1 January 2027. The definitive date of entry into force will be determined by Royal Decree. Share option rights granted on or after 17 April 2025 may also be eligible for the scheme. For this to apply, the share option rights must not yet have been included in payroll tax as at 31 December 2026, and the other conditions must be met. In that case, your company must apply to the RVO for the decision by 31 December 2027 at the latest.
Tip! Check in good time whether your company is eligible for an RVO decision. Also consider whether employee participation can help you attract, reward and retain talent.
Employers must also pay a so-called ‘freedom contribution’ to fund rising defence expenditure. The government intends to collect most of this additional burden through an increase in the contribution to the Disability Fund (Aof). According to estimates, this increase will generate €1.5 billion in additional contribution revenue in 2027. From 2028 onwards, this will amount to €1.7 billion per year on a structural basis.
The high and low Aof contribution rates have not yet been finalised. The contribution rates will be announced at a later date, alongside the annual contribution rates for employees’ insurance schemes. As a result, it is not yet clear exactly how much your employer’s contributions will increase.
Tip! Allow for higher employer’s contributions in your 2027 staff budget. Adjust your payroll cost calculations as soon as the high and low AOF contribution rates for 2027 have been officially set.
Are you buying a property in which you will not be living yourself on a long-term basis? If so, you will pay transfer tax at the standard residential rate. This applies, for example, to a let property or a holiday home. From 1 January 2027, this rate will fall from 8% to 7%. The 2% rate for a property in which you will be living yourself and the first-time buyer’s exemption remain unchanged.
Please note! This reduction does not apply to commercial premises. In the case of mixed-use properties, conversions and property development projects, there may be some debate as to which part qualifies as a residential property. The use and condition of the property at the time of acquisition play an important role in this regard.
Due to the rate reduction, it may be worth reconsidering the timing of the transaction. You should also take other factors into account, such as financing, return on investment, VAT and the legal structure.
Tip! Before signing the purchase agreement, have an assessment carried out to determine which rate applies to your situation. In doing so, investigate whether it is sensible and feasible to postpone the transfer of title at the solicitor’s office until after 1 January 2027.
Certain non-reimbursed healthcare costs are currently tax-deductible under specific conditions. These include specific medicines, medical aids, dietary costs, transport and additional family care. The relief only applies after any reimbursements and an income-related threshold have been taken into account.
The Government is abolishing the deduction for specific healthcare costs with effect from 1 January 2028. The associated scheme for reimbursement of specific healthcare costs, the TSZ scheme, will also be abolished. For people with a chronic illness, the Government is working on a targeted compensation scheme. The bill does not include any transitional provisions. The measure primarily affects people with a chronic illness, a disability or structurally high, non-reimbursed healthcare costs. Entrepreneurs and directors/major shareholders may also face higher net personal tax liabilities as a result. The financial impact varies greatly, as not every out-of-pocket healthcare expense is currently tax-deductible.
Tip! Make a list of your recurring deductible healthcare costs. This will show which tax benefits may be lost from 2028 onwards and to what extent a future compensation scheme will cover them.
What tax proposals for entrepreneurs did the Dutch Government announce on Prince’s Day 2026? We have listed ten key proposals for you.
READ MORE
The entrepreneur’s allowance comprises the self-employed person’s allowance (in Dutch: zelfstandigenaftrek), the allowance for research and development (in Dutch: aftrek voor speur- en ontwikkelingswerk), the co-worker’s allowance (in Dutch: meewerkaftrek), the start-up allowance in the event of incapacity for work (in Dutch: startersaftrek bij arbeidsongeschiktheid), and the cessation allowance (in Dutch: stakingsaftrek). These allowances may be deducted from business profits for the purposes of income tax.
Foreign taxpayers are taxed in the Netherlands to the extent that they receive Dutch income. Dutch income includes, amongst other things, the profit generated by a foreign entrepreneur’s permanent establishment in the Netherlands. The question is whether the entrepreneur’s allowance may be deducted in full from the profit of this permanent establishment or whether a different allocation must be made?
For the portion of the foreign entrepreneur’s profit that is taxable in the Netherlands, the letter of the law first requires the global profit to be determined, i.e. the foreign entrepreneur’s total profit, including profit earned outside the Netherlands. The Tax and Customs Administration states that the entrepreneur’s allowance and the SME profit exemption (in Dutch: mkb-winstvrijstelling)are deducted in full from these worldwide profits. The profit taxable in the Netherlands is that part of the worldwide profit, after deduction of the entrepreneur’s allowance and the SME profit exemption, which is attributable to the Dutch permanent establishment.
The business allowance is therefore not deducted in full from the profits of the permanent establishment, but in proportion to the ratio of Dutch profits to total worldwide profits.
The Tax and Customs Administration states that the portion of the SME profit exemption that may be charged against the profit taxable in the Netherlands must be determined in the same way as for the entrepreneur’s allowance.
Please note! According to the Tax and Customs Administration, the fact that the entrepreneur’s allowance and the SME profit exemption must be determined in the manner described above also follows from a 2010 ruling by the Supreme Court (in Dutch: Hoge Raad).
The Tax and Customs Administration has provided an answer to the question of whether an entrepreneur residing abroad is entitled to deduct the full business allowance (in Dutch: ondernemersaftrek) from their Dutch profits.
READ MORE
In principle, the Tax and Customs Administration has eight weeks to process your VAT refund claim. If this takes longer, you are entitled to compensation for tax interest provided that the VAT refund relates to a previous year and 1 April has already passed.
Example
The Tax and Customs Administration receives your request for a VAT refund for the fourth quarter of 2025 on 20 January 2026. If you have not yet received a refund decision from the Tax and Customs Administration by 1 April 2026, you are entitled to compensation for tax interest from 1 April 2026.
The period over which tax interest is calculated begins on 1 April or eight weeks after receipt of your claim (if this is later than 1 April). The period runs until fourteen days after the date of the refund decision.
Continuation of example
If the Tax and Customs Administration issues a refund decision dated 15 June 2026, it must reimburse 5% tax interest for the period from 1 April 2026 up to and including 29 June 2026.
Has the Tax and Customs Administration wrongly rejected your VAT refund claim? If so, you must lodge an objection in good time, i.e. within six weeks of the date of the rejection notice. If the Tax and Customs Administration subsequently grants the VAT refund, you are also entitled to reimbursement of tax interest.
Please note! In response to enquiries on this matter, the Tax and Customs Administration has stated that there is no entitlement to reimbursement of tax interest if the original application for a VAT refund was submitted too late and/or if the appeal against the rejection notice was lodged too late.

Have you applied for a VAT refund and is the processing taking a long time? If so, you may be entitled to compensation for tax interest.
READ MORE
It is laid down in law that taxpayers have the right to inspect their own tax files held by the Tax and Customs Administration. In the letter, the State Secretary sets out how the implementation of this right of access to tax files will take shape in the coming years, what the intended timetable is and what exceptions will be made to the right of access.
At present, the Tax and Customs Administration does not yet have a centralised file system: the information in the tax file remains highly fragmented across dozens of unlinked systems. To facilitate the right of access to tax files, the Tax and Customs Administration will therefore need to implement a change in its working methods. The aim is to achieve a structured, externally oriented and accessible filing system, according to the State Secretary. The documents in the tax file will be made available digitally in stages over the coming years.
Under the ‘Keuze digitaal’ programme currently being implemented within the Tax and Customs Administration, decisions, invitations, reminders and submitted documents will gradually become available on MijnBelastingdienst (Business) by 2030. This will later be expanded to include standard letters and automated messages, followed by information from individual files, for example regarding the processing of a tax return.
The letter also sets out a provisional timetable, which includes the planned introduction of the right of access to tax records:
For Customs, the right of tax inspection would only apply to excise duties and consumption taxes. However, the State Secretary is excluding these levies from the right of tax inspection. The State Secretary points out that this does not mean that Customs is not committed to further improving the information position and legal protection of taxpayers.
In a letter to the House of Representatives, the State Secretary for Finance has outlined the current situation regarding the introduction of the right of access to tax records. This right of access will be introduced in phases.
READ MORE
The introduction of the legal presumption does not mean that every contractor working at an hourly rate below €38 is automatically employed by the company. It does, however, mean that the presumption of an employment relationship is accepted. The contractor may rely on this presumption, but the company has the option to demonstrate that no employment contract exists.
If the company fails to prove this, the contractor is entitled to all the protection afforded by employment law. This includes continued payment during holidays and sick leave, and protection against dismissal
The contractor may rely on the legal presumption, but it has effect only under civil law. This means that the UWV, the Tax and Customs Administration and the Labour Inspectorate will not assess this legal presumption. They will continue to carry out their own investigations based on the elements of work, pay and a relationship of authority.
The legal presumption will come into force immediately on 31 December 2026. Do you have a contractor who is already carrying out work for you before 31 December 2026 at an hourly rate of less than €38? And will that contractor still be doing so from 31 December 2026 onwards? If so, from 31 December 2026 there will be a presumption that this contractor is employed by you.
The legal presumption of an employment contract for an hourly rate below €38 will come into force on 31 December 2026. What does this mean for you as a client or company?
READ MORE
Solvit is a body established by the European Commission that mediates in disputes regarding the correct application of EU law. Solvit’s services are free of charge.
The issues you can bring to Solvit are diverse. These include problems related to visas, child benefits, or pensions. For businesses, issues concerning trade and services, the recognition of professional qualifications, and VAT refunds are particularly relevant.
Please note!You cannot use Solvit if you have a problem with another business, if you have a problem as a consumer, or if you are seeking compensation. Solvit also cannot help if your case has been brought before a court.
A complaint or problem can be submitted online. You must indicate the nature of the problem and which government agency you wish to report the issue to. You may also attach relevant documents, such as correspondence. After submission, the Solvit center in your own country will contact you to prepare your case and then forward it to the Solvit center in the country to which your complaint relates. The goal is to resolve a problem within ten weeks.
On the Solvit website, you’ll find numerous examples of cases that have been resolved with Solvit’s help. These include, for example, the failure to refund VAT or delays in doing so. Another case involves the refusal to issue a certificate of inheritance. Yet another example involves the refusal to allow a product onto the French market, even though it complied with European regulations.
Solvit can also be contacted if you need advice on your EU rights. If necessary, you will be referred to services that can provide better assistance. Requests for advice are answered within a week.

Are you, as a citizen or business, facing problems because a government agency in another EU country, Iceland, Liechtenstein, or Norway is not complying with EU law? If so, you can try to resolve this through Solvit.
READ MORE
If you owe taxes, you will receive a notice from the Tax and Customs Administration. The new account number will be included in the notice regarding the taxes due.
Please note!The new account number does not affect the payment method. For example, online payments will still be possible.
If you pay the Tax and Customs Administration periodically via direct debit, you do not need to do anything. The payments will be automatically transferred to the new account number.
You only need to be careful if you have arranged a recurring payment differently, for example via a recurring transfer with your bank. In that case, you must ensure that the account number is updated yourself.
If you accidentally use the “old” account number for a payment to the Tax Authority, your payment will still be forwarded to the Tax Authority and processed there for the time being. The Tax Authority has made arrangements with ING regarding this, so that taxpayers are not penalized.
To pay a provisional or final income tax assessment, you can use the new account number starting April 20, 2026.
The Benefits Service is also switching to Rabobank and will therefore have a new account number starting May 1, 2026. From that date, you can make payments to the Benefits Service using the new account number NL04 RABO 0200112244. The Benefits Service will make its first payments from this number on Monday, June 22, 2026.
Please note! Here too, if you make a payment to the old account number, the payment will be forwarded to the Tax and Customs Administration’s new account number for the time being.
Due to the change in account numbers, the Tax and Customs Administration strongly warns against phishing. Criminals regularly attempt to collect non-existent tax debts from taxpayers via email, text message, WhatsApp, or by phone. However, the Tax and Customs Administration never collects taxes in this manner. If you are unsure whether a message is genuine, follow the step-by-step guide on the Tax and Customs Administration’s website and verify the account number.
As of May 1, 2026, the Dutch Tax and Customs Administration and the Benefits Service will switch from ING to Rabobank. This means that the account numbers will also change.
READ MORE
For businesses that buy or sell goods, cash payments of €3,000 or more will no longer be permitted starting January 1, 2026. It does not matter whether the business is buying from or selling to another business or to a private individual. In all cases, cash payments of €3,000 or more are prohibited.
Please note! A private individual may accept a cash payment exceeding €3,000 from another private individual, for example, when selling on a marketplace.
The €3,000 limit is intended to make it more difficult to launder cash derived from illegal transactions and thereby also combat terrorism. The limit is also intended to ensure that payment transactions remain accessible.
The fine for violating the ban is set at a fixed base amount of €10,000. The Wwft Supervision Bureau, a division of the Tax and Customs Administration, oversees compliance with the ban.
Special circumstances, such as financial capacity, may justify reducing the fine. On the other hand, repeated violations of the prohibition may justify increasing the fine. For example, a fine of €20,000 may be imposed if the prohibition is violated again within five years of a previous fine.
Please note! Criminal proceedings may also be initiated under the Economic Offenses Act.
Starting January 1, 2026, Dutch merchants may no longer make or accept cash payments of €3,000 or more. The base amount of the fine for violating this prohibition is a fixed amount of €10,000.
READ MORE
It is particularly common among migrant workers for employers to provide accommodation and deduct an amount from the employee's wages for this. In the case of the minimum wage, this deduction may still be a maximum of 25% of that wage in 2025.
The government believes that the deduction can encourage a model of earning and dependence on the employee. This can lead to the exploitation of migrant workers. The government therefore wants to abolish the scheme.
The proposal is to reduce the deduction by 5% per year from 2026 and to completely abolish the possibility of deducting housing costs from the statutory minimum wage from 2030.
| Year | Maximum deduction percentage |
| 2025 | 25 |
| 2026 | 20 |
| 2027 | 15 |
| 2028 | 10 |
| 2029 | 5 |
| 2030 | 0 |
Tip! Employers will still be allowed to provide housing for their employees from 2030 onwards. However, it will no longer be possible to deduct part of the costs from the statutory minimum wage.
The proposal has been submitted for internet consultation. Responses to the proposal can be submitted until June 6, 2025.

In the Netherlands in 2025, employers will be allowed to deduct a maximum of 25% of the minimum wage from an employee's statutory minimum wage to cover the costs of housing. The proposal off the Dutch government is to reduce this percentage by 5% annually from 2026 to 2029.
READ MORE

Contact
Schoutlaan 7
6002 EA Weert
0495 53 07 55
info@w-o.nl
W&O Accountants en Adviseurs
Algemene Voorwaarden
Klachtenregeling
Klokkenluidersregeling
Privacyverklaring
W&O Registeraccountants
Algemene Voorwaarden
Klachtenregeling
Klokkenluidersregeling
Privacyverklaring
