
On 29 January 2019 the European Regulation on matrimonial property law came into force. This regulation will be applied by judges in each Member State of the European Union. Judges will apply this regulation for 'international divorces'.
A case is considered 'international' if you and your spouse have a foreign nationality or multiple nationalities. This regulation can also apply if you have lived abroad together immediately after your marriage
Judges will first assess whether they are qualified to hear the case. If the court decides to assume jurisdiction, it must first check which law applies. It is important to know that the Dutch judge cannot always apply Dutch law. The regulations and treaties specify which laws the court must apply.
This legislation only concerns matrimonial property law. The legislation regulates whether Dutch law applies to the general community of property (until 2018) or limited community of property (from 2018) or if the laws of another Member State must apply. This decision can have very different consequences. While the new regulations are not explicitly concerned with alimony, it is quite possible that different laws regarding alimony must be applied by the Dutch court.
Important! The new legislation only applies to matrimonial property law and not, for example, to the establishment of alimony obligations.
The judgment determines that the following laws must apply:
Important! The court may make an exception and decide that the right of the first joint residence does not apply if the parties subsequently moved to another country for a significantly longer period and would be expected to have assumed that the rules of that country would apply.
You may be affected by these new rules if you were married on or after January 29th, 2019, or if you were married before then but only legally registered this marriage after January 29th, 2019. For cases prior to that date, the Hague Matrimonial Property Convention of 1978 still applies. For marriages declared prior to 1 September 1992, other rules apply, namely the rules laid down in an important judgment of the Supreme Court.
Tip! If your marriage is ‘international’ make sure you are aware which law applies. This will avoid any unpleasant surprises if you subsequently divorce at a later stage.
It might be the case that spouses opt to apply the law of a particular country. This is called a choice of law. The legislation determines when that choice of law is valid. For parties living in one EU Member State, for example, the choice of law must comply with the rules of a prenuptial agreement in that Member State. Under Dutch law this is only possible when confirmed via a notary. You can then choose the right of habitual residence or the nationality of one of the spouses.
Tip! Check carefully whether a choice of law is valid. If the choice of law does not prove valid, this may have major and possibly unpleasant consequences.
If no choice of law has been made the new legislation will apply.
Does your situation resemble an ‘international divorce’? Make sure you get good advice.

New European legislation now applies to couples planning to divorce if the couple has lived abroad directly after their marriage, or if both (also) are foreign nationals. This judgment applies to matrimonial property law and determines whether the divorce should fall under Dutch law, or that of a foreign country.
READ
Snel has informed the Dutch Parliament on this matter. If the UK leaves the EU on March 29th without a deal, the UK will become a so-called ‘third country’ and different rules will apply to trade and tax agreements.
According to the Minister of Finance, a no deal Brexit has corporate tax consequences for tax groups in cases where a so-called ‘top holding company’ is established in the UK. A no deal Brexit would mean that such a tax group is automatically terminated , according to the Minister.
Dutch citizens resident in the UK for whom income is (partially) taxed in The Netherlands will lose the right to personal deductions after Brexit. There are numerous other examples of a no deal Brexit having direct consequences for companies and citizens.
Snel wishes to implement a ruling where the UK will continue to be treated as a member of the EU for the remainder of the current financial year. This will ensure that the current tax regime continues to apply in the event of a no deal Brexit. In addition, he proposes transition laws for companies, for example to prevent different tax regulations being applied during the same financial year.
Menno Snel, Dutch Minister of Finance believes that in the case of a hard Brexit on March 29th, 2019, a transitional tax law, apart from customs legislation, is desirable . A hard Brexit means an immediate change in tax procedures for companies and citizens.
READ
Important!Certain changes planned by the Cabinet still require parliamentary approval.
As of 2019 the income tax rates will be lowered, as also planned for the following year. Most deductible items can be deducted at a lower rate in the years ahead. Next year, the corporate income tax rate for the first € 200.000 of profit will fall from 20% to 19%. Consult your tax advisor to decide if it is therefore lucrative for you to postpone confirming your revenue and to increase your costs. It might also be wise for you to pay deductions on items such as donations and healthcare already this year, where possible.
Make full use of your remaining allocation of 1.2% in the labor costs scheme. You can still use any remaining allowance for Christmas gifts, bonuses or to organize a staff Christmas Party. Remember that the tax authorities generally accept expenditure of up to € 2,400 per employee.
The lower VAT rate will be raised from 6% to 9% as of January 1st, 2019. Goods that have already been invoiced and services that will be provided in 2019 will not be charged at the increased rate. If you deliver goods and services that are covered by the lower VAT rate you can make use of this by invoicing before the end of this year.
Maximize your investment allowance with effective planning of your investments. For larger sums, the investment allowance decreases as the amount of your investment increases. For example, an investment of € 100.000 in 2018 delivers a small-scale investment allowance of € 15.863. If you spread this investment over 2018 and 2019 by investing € 50.000 each year, this will deliver a small-scale investment allowance of € 28.000.
Energy saving investments can be eligible for the Energy Saving Allowance. This amounts to 54.5% this year, reducing to 45% next year. This is a good reason to make energy saving investments before the end of this year. The moment at which you enter into any legal obligation in this area determines the moment at which you have the right to request extra deduction.
Did you make a profit in 2017 but are you expecting to close 2018 with a loss? Submit your application for a provisional loss settlement after your income tax or corporation tax return for 2018.
You can then offset 80% of the probable loss with the profits from 2017. Any differences from the declaration will be corrected at the final assessment.
As of 2019, electric cars that cost more than € 50,000 face an additional tax of 22%, provided that the catalog value is above € 50,000. Therefore, if you were thinking of buying an expensive electric car it is wise to do this before the end of 2018. The valuation of the wages in kind of just 4% regarding the car is yours for a maximum of five years.
As an entrepreneur in The Netherlands, are there any financial measures that you can still take this year that are beneficial to your company? How can you already start to plan for changes that will apply in 2019? Here are our top 7 practical tips:
READ
De voor Nederlandse bedrijven belangrijkste punten in het Brexit-akkoord zijn:
Het VK blijft na het officiële vertrek uit de EU op 29 maart 2019 voorlopig in de interne markt. Deze transitieperiode duurt tot eind 2020. Voorlopig komen er dus geen extra handelstarieven. Het VK en de EU onderhandelen in de transitieperiode over nieuwe handelsafspraken. Komen ze er niet op tijd uit, dan kan de transitieperiode eenmalig met nog eens maximaal twee jaar worden verlengd.
De EU wil 'onnodige' handelsbelemmeringen wegnemen, maar dat hangt af van de bereidheid van de Britten om zich te houden aan de regels van de EU. Hoe meer regels het VK volgt, hoe minder checks en controles er aan de grens nodig zijn. Hoe hecht de handelsrelatie tussen de EU en het VK wordt, is dus nog niet duidelijk. De Britse politiek zal zich ook hierover nog moeten uitspreken.
In het uittredingsakkoord is opgenomen dat tijdens de transitieperiode tot eind 2020 voor de visserij alles bij het oude blijft. Dit betekent dat Europese vissers in die periode mogen vissen in de Britse wateren. Hoe de visserij in Britse wateren eruit zal zien na 2020 zal worden uitonderhandeld tijdens de transitieperiode.
Voor mensen uit de EU die nu in het VK werken, verandert er niets. Dit geldt ook voor Britten die in de EU werkzaam zijn.
Als het Britse Lagerhuis instemt met het conceptakkoord, dan beginnen de dag na het vertrek van de Britten op 29 maart de onderhandelingen over de toekomstige relatie tussen de EU en het VK. Als er een parlementair 'No' komt, dan is er geen akkoord en vertrekt het VK zonder afspraken uit de EU.
Tip! Ondanks dat er nu een conceptakkoord ligt, blijft er veel onzeker en een harde Brexit is nog niet van de baan. Bereid u dus voor en kijk welke gevolgen dat voor u kan hebben, bijvoorbeeld met de Brexit Impact Scan of via www.hulpbijbrexit.nl.
De 27 lidstaten die overblijven in de Europese Unie (EU) hebben ingestemd met het akkoord dat het vertrek van het Verenigd Koninkrijk (VK) regelt. Premier May moet dit akkoord in december nog wel door het Britse Lagerhuis loodsen en ook het Europese parlement moet nog instemmen.
READ
The Euro Vignette (that The Netherlands continues to use) will therefore be phased out. The kilometer fee may only be based on distance, and not on time.
Caution! Even with this new ruling each country can still determine for themselves whether they implement a kilometer fee.
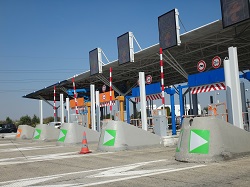
The possibility of congestion charges – extra costs for using busy roads that often experience traffic jams - is also under discussion. Vehicles that produce little or no emissions are eligible for a discount on any congestion charges that they are obliged to pay.
Peter van Dalen, member of the Transport Commission of the European Parliament, supported this proposal: "More freight should be transported by rail and canal. These are environmentally friendly methods of transport. The waterways offer great opportunities for congestion free haulage. The European Parliament is focusing on multimodal transport that has lower CO2 emissions. Above all, infrastructure usage will be taxed more fairly, based on kilometers driven and not on time."
Caution! Kilometer charges are now only allowed to be levied per kilometer, and not on time.
The current regulations for delivery vans will apply until the end of 2027. This is limited to lightweight delivery vans. Vans of 2.4 tons or more will have to pay the kilometer fee as of 2023.
Source: ttm.nl
From 2023, EU member states that wish to charge trucks and delivery vans for use of their road and traffic infrastructure can only do so with a kilometer fee. This proposal was accepted by the European Parliament on 25th October 2018.
READ
These rate adjustments reveal that the Cabinet is shifting towards a flat tax rate, or a taxation system with the same rate for everyone. This is not something that is currently ready for implementation. However, as of 2021 there will only be two tax rates, 37.05% and 49.5%.
The tax rates will start to change in 2019. The first tax bracket, applying to incomes up to €20,142, will increase by 0.1%-punt from 36.55% to 36.65%. The rates for the second and third brackets, covering incomes between €20,142 and €68,507, will decrease significantly, from 40.85% to 38.1%. Currently those earning over €68,507 pay a rate of 51.95%. Next year this will be reduced slightly to 51.75%.
Next year someone with an income of €35,000 will benefit from these changes by paying €380 less tax. Those on higher salaries will benefit more. Someone with an income of €65,000, for example, will enjoy a saving of €1,215. Those on an income of up to €20,000 will pay a maximum of €20 more in tax.
From 2021 there will be just two tax brackets in box 1. A rate of 37.05% will apply to those on incomes up to €68,500. Incomes exceeding this amount will be taxed at a rate of 49.5%.
Tax % in box 1
Income of max € 20.142 Income of max € 34.404 Income of max € 68.507 Income > € 68.507
2018 36.55 40.85 40.85 51.95
2019 36.65 38.10 38.10 51.75
2021 37.05 49.50
Warning! The switch to two tax brackets in box 1 will only apply to those who are not yet entitled to AOW. For those entitled to AOW different rates will apply. Three brackets will continue to apply to those eligible for AOW.
Due to inflation and other factors, the tax rates will be indexed annually. Until 2024 this will not apply to the starting point of the top rate. This will remain frozen at the current level of €68,507. Taxpayers will therefore reach the top rate earlier. The expected result of this is that around 7% of taxpayers will be taxed at the highest rate. Without this freezing only 5.5% of taxpayers would be taxed at the top rate.
Major changes in Dutch income tax procedures are heading our way. Firstly, the box 1 income tax rates for incomes above €20,142 will be reduced as of 1st January 2019. In 2021 two tax brackets will disappear, meaning only two will remain.
READ
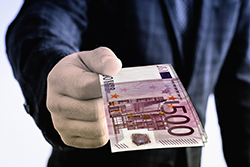
The government agreement had established that the ruling concerned small employers. It was subsequently decided that larger employers would also be considered. Every employer can make use of the ruling if they meet the conditions. This will make the procedure more affordable.
Employers are required to pay transition compensation to any employee who is dismissed after two years of sickness or disability related absence. This compensation must be paid by the employer, and the maximum permitted amount is equivalent to the salary that was paid during the two years of illness. The purpose of this regulation is to limit the costs of prolonged absence and dismissal on the employee. It is also intended to prevent long term dormant employment contracts.
You can apply for compensation from the UWV from the 1st of April 2020, provided that the application is made within 6 months of the payment of the complete transition compensation. Compensation can be applied retroactively to transition payments that were made from 1st of July 2015 onwards. This is possible between the 1st of April 2020 and the 30th of September 2020. These dates were confirmed after discussion with the UWV. In this discussion the UWV made it clear that they needed time to prepare for this regulation.
Large and small employers can be considered for compensation procedures relating to transition compensation for lengthy employee absenteeism. This was confirmed by Minister of Koolmees of the Employment and Social Affairs department in a response to questions from the Green-Left division in the Dutch Senate. The rule will apply as of April 1st, 2020.
READ
A brief explanation of the most notable changes in the area of taxation is provided below.
Please note! The Upper and Lower House still have to vote on these changes.
From 2021 there will be only two instead of four bands for income tax (for people below state pension age). The basic rate of 37.05% will then apply up to an income of € 68,507. Above this threshold the top rate of 49.5% will apply. In 2019 the current rates of 36.55%, 40.85% and 51.95% will be changing to 36.65%, 38.10% and 51.75%.
Under the new system, from 2021 people of state pension age will continue to be subject to different rates, as is the case now. These new rates will be 19.15%, 37.05% and 49.5%.
The rate of income tax in box 2 applicable to income from substantial shareholdings will increase to 26.25% in 2020 and 26.9% in 2021. This increase is lower than that previously announced in the coalition agreement (to 27.3% and 28.5% respectively). The current rate is 25%.
Over the next few years the employed person's tax credit will be increased incrementally, up to a maximum of € 3,941 in 2021. From 2019 it will be reduced to zero from an income of € 36,344. The aim of this rise in employed person's tax credit is to make work (or working more) pay.
With effect from 1 January 2019 the reduced rate of VAT will increase from 6% to 9%. This rate applies to foods, sporting activities and recreation, for example.
In the coalition agreement the governing parties agreed to reduce the rate of corporation tax. For taxable amounts (profits) up to € 200,000 the rate of corporation tax will be reduced from 20% to 19%. It will be cut further to 17.5% in 2020 and to 16% in 2021.
However, the rate of corporation tax applied to taxable amounts above the € 200,000 threshold will not be reduced to the previously agreed level of 21%, but will be a maximum of 22.25% in 2021. In 2019 this top rate of corporation tax will be lowered to 24.3%.
The permitted depreciation of property used by a company for its own purposes is being restricted for purposes of corporation tax. At present such property may be depreciated down to 50% of its WOZ value (value for the purposes of the Valuation of Immovable Property Act). With effect from 1 January 2019 it may not be depreciated below 100% of its WOZ value.
Example: let's assume that the WOZ value of a property is € 1,000,000 and the book value is € 900,000. Previously, it was possible to depreciate this property down to 50% of its WOZ value, i.e. to € 500,000 in this example. Under the new plans it will no longer be permitted to depreciate it below the WOZ value, which means that no further depreciation is possible in this example.
Please note! This measure only applies to entities subject to corporation tax.
In 2019 losses for corporation tax purposes may only be carried forward and offset against profits for six years instead of nine. Losses incurred before the 2019 financial year may still be carried forward and offset against positive results for nine years.
In spite of the considerable controversy surrounding the issue, dividend tax will be abolished from 1 January 2020. The main reason for abolishing this tax is to increase the attractiveness of the Netherlands as a location for international businesses.
The introduction of a withholding tax on dividends from 1 January 2020 is intended to prevent tax avoidance. This will mean that intercompany dividend payments made to entities in low-tax countries will be taxed. The same will apply in the event of abusive practices, according to the Budget Memorandum.
A withholding tax on interest and royalties will also come into force from 1 January 2021.
The current scheme for determining the private use of a company bicycle is being simplified by introducing an addition to taxable income based on a fixed percentage with effect from 1 January 2020. This addition will amount to 7% of the recommended retail price set by the manufacturer.
With effect from 1 January 2019 the duration of the 30% scheme for employees from outside the Netherlands is being reduced from eight to five years. There will be no transitional arrangements, which means all current schemes will also be shortened by three years.
All current decisions by the tax authorities relating to the scheme that are valid up to and including 1 January 2022 will lapse with effect from 1 January 2019. As a result, the tax-favourable scheme under which such employees can choose to be treated as foreign taxpayers for a portion of their income will also be discontinued from 1 January 2019.
Yesterday, Dutch Minister of Finance Wopke Hoekstra presented the 2019 Budget Memorandum and the 2019 Tax Plan. The government is focusing on reducing the tax burden on employment, combating tax avoidance and evasion, improving the attractiveness of the Netherlands as a business location and making the tax system greener and more easily enforceable.
READ
The increase in the lower rate of VAT applies to essential supplies such as food and beverages as well as books and magazines. Some services are also included, such as hairdressing, shoe repairs and bicycle maintenance. Other affected services include hotel stays, sauna visits and public transport.
The consumer price for these goods could be increased by 3% due to the planned VAT increase. (109/106 = 2.8).
If you sell one or more of these products or services, you will more than likely need to adjust your prices. Just like other businesses, you will need to take this inflation into account in your new prices as of 1st January 2019.
Your administrative procedures will also have to adjust to these changes. Your bookkeeping records should show the quantity of goods and services that you currently sell at the lower VAT rate and what consequences this increase will have on your VAT payments. The same will apply to your purchases to which the lower VAT rate applies, and the subsequent deductions.
The VAT increase will need to be reflected in your invoicing, to ensure that the correct VAT rate is always calculated. Accidentally applying the incorrect rate to invoices causes your company an extra tax burden.
Have you already sent invoices for goods and services that will be supplied in 2019? It is not necessary to pay the difference between the old and new VAT rates. There is also no need to adjust your administration for this, or to send new invoices.
Warning! The increased VAT rate will need to be applied to all your proposals for relevant products or services that will be provided after January 1st 2019.
As of the beginning of next year the lower VAT rate will be raised from 6% to 9% in The Netherlands. This has several consequences that should be anticipated by businesses in advance of the increase. Examples include the implementation of possible price increases or necessary adjustments to administrative procedures.
READ
The amounts specified as the minimum wage apply to an entire working week. This is usually 36, 38 or 40 hours per week. This depends on the sector where your company operates and any possible CAO arrangements in this sector. As of July 1st, the minimum wage will be 1.03% higher than in the first half of 2018. This raises the gross minimum wage to €1,594.20 per month, €367.90 per week and €73.58 per day.
A lower minimum wage applies to younger people, as shown in the table below.
If you hire a third party, or they make themselves available to you as an independent service provider, there is a risk that the tax authorities see the agreement as employment. This can be the case during long term assignments. You can prevent this by working with an agreement template.
The tax authorities have made it known that no exceptions will be made, and fines will be issued if no taxes or insurance contributions are made while there is evidence of employment. The tax office will enforce instances of malpractice. As of July 1st 2018, the authorities will no longer only focus on the most serious cases, but on other instances too. The tax authorities can punish malpractice of they can prove any of the following:
As of 1st July 2017, a new Working Conditions Act came into effect. An example of a change is that employers now have the right to anonymously refer an employee to a company doctor without their consent, even if there is no evidence of illness or absenteeism. There is a transition period of 1 year for employers, allowing existing contracts detailing working conditions to be adjusted. During this transition period existing contracts can be renewed or provided with a supplement. This transition period expires on July 1st 2018, and from that date onwards all employers must be aligned to the new demands of the Working Conditions Act.
If your staff still have outstanding vacation days from 2017, these must now be used by July 1st 2018, as per the new rules. If not, they will be forfeited, unless an exemption applies.
In the following cases the unused vacation days will be forfeited after 5 years:
You can become an own risk bearer for the WGA (Werkhervatting Gedeeltelijk Arbeidsgeschikten – work resumption for the partially disabled). This means that from the start of the WGA insurance you carry the risk for partial inability to work and temporary complete inability to work of your (ex) employee, or that you insure this privately either fully or partially. You also carry the risk for death benefit payments of one-month WGA to relatives of employees with a WGA insurance who fall under the own risk clause.
Because you accept these risks as a risk bearer for the WGA, you do not have to pay the premium component WGA of the sector premium (WHK).
You are required to submit a request to become an own risk bearer for WGA to the tax authorities. You can begin bearing the own risk for WGA on either January 1st or July 1st. Your request must be received by the tax authorities at least 13 weeks prior to the commencement date. If you are considering becoming an own risk bearer as of January 1st 2019, you would need to submit your request by October this year. It is wise to determine in advance if this action is interesting and if you can meet the conditions that are applied. We are of course happy to assist with this.
The necessary changes will be effective as of July 1st. As an employer what do you need to consider? The minimum wage rates and deadlines for usage of vacation days are items that need to be looked at.
READ

Weert branch
Schoutlaan 7
6002 EA Weert
0495 53 07 55
info@w-o.nl
W&O Accountants en Adviseurs
General terms and conditions
Complaints procedure
Whistleblower policy
Privacy statement
