
These questions are now arising, with the prospect of a large-scale vaccination programme getting under way next year. Vaccinations will be given on the basis of a priority list.
Can an employer oblige an employee to receive a vaccination? The answer to this question is ‘no’. An employee has a right to physical integrity and this is enshrined in the Constitution. It is therefore up to the employee to decide whether or not to be vaccinated. Vaccination takes place on a voluntary basis.
An employer cannot therefore oblige his or her employees to receive a vaccination. Although the employer has a duty of care with regard to an employee’s health and safety and his or her working conditions, this does not extend to being able to force the employee to be vaccinated. It is also not permitted to put the employee under pressure to receive a vaccination. After all, we are talking here about health data and this is subject to privacy legislation.
Please note:If an employee who has not been vaccinated falls ill, the employer also has an obligation to continue paying his or her salary in this situation.
During a job interview it is also not permitted to ask the candidate whether he or she has been or plans to be vaccinated. After all, this is also health data. Health data is a specific item of personal data whose processing is prohibited, unless a statutory exemption applies. The explicit consent of the employee is insufficient, as – in view of the relationship of dependency – it is possible to question whether the consent was given voluntarily.
An obligation to be vaccinated can only be included as a job requirement if there is a legitimate aim and the means of achieving that aim are appropriate and necessary. After all, this means that a distinction is being introduced between staff who have and staff who have not been vaccinated. As mentioned above, the principle of physical integrity and the right of self-determination apply. Including an obligation to be vaccinated in a job requirement is not justified by a legitimate aim.
If vaccination is essential to be able to carry out the work in question safely, as in the case of a candidate for a healthcare role, the employer can demand that the candidate undergo a medical examination. On the basis of the Medical Examinations Act, it is permitted for the company doctor to ask the candidate whether he or she has been vaccinated. The company doctor will subsequently indicate whether or not the candidate is suitable for the role. The reason for this conclusion is not given.
Can an employer oblige healthcare workers on permanent contracts to receive a vaccination? This is a difficult question to answer, as everything is new when it comes to the coronavirus and there is no case-law in this area. We can infer from past case-law, however, that in such cases the court will often weigh up the individual and collective interests.

Can an employer oblige an employee to receive a vaccination? Are you allowed to ask a candidate whether he or she has been vaccinated during a job interview? Can you include an obligation to be vaccinated in the job requirements? Is the answer to this last question different in the case of healthcare personnel?
READ
The fixed budget under the work-related expenses scheme (WKR) has been expanded this year. Up to a wage bill of € 400,000 the fixed budget amounts to 3%, with 1.2% applying to the excess amount. Assess the fixed budget you have remaining and make full use of it. Be sure to take advantage of the cost-efficiency threshold of € 2,400 per person per year. Up to this amount the Tax and Customs Administration will regard any allowances and benefits in kind granted as customary allowances and benefits. Only make use of the group scheme under the work-related expenses scheme if this will work out in your favor. As the fixed budget has been increased, this is less often the case than it was last year.
If your companies currently form part of a tax group, it may be beneficial to disband it. The tax group pays corporation tax on the combined profits of all the companies. In view of the increasing gap between the lower and higher rates of corporation tax, disbanding a tax group is becoming a more attractive option. From 2021, after all, there will be a difference of 10 percentage points between the rate in the first band and the higher rate (15% and 25% respectively). The lower rate will apply to the first € 245,000 of profits from 2021 and even to the first € 395,000 of profits from 2022.
If you purchase a commercial property, this year you will owe transfer tax at a rate of 6%. This rate will increase to 8% from 2021. We therefore recommended that, if possible, you complete a planned purchase of a commercial property before 2021.
As an entrepreneur, you are best off waiting until after 31 December to transfer liquid assets that generate low returns, such as cash in your business bank account, to your private assets. In this way you will avoid the relatively high tax in box 3. Conversely, it makes sense to transfer any necessary cash from your private assets to your business account before 31 December this year.
As a private individual, you can avoid the high rate of tax that applies in box 3, in particular to savings, by setting up a ‘savings company’ (‘spaar-bv’) or a mutual fund. You will then pay around 38% tax on the return actually received up to € 245,000. This is considerably less than the 0.59% to 1.76% tax that you will pay on your savings balances in box 3 in 2021, although you need to bear in mind that the exempted income in box 3 is being increased to € 50,000 per person in 2021.
The rate of tax on substantial shareholdings (box 2) will be increasing from 26.25% to 26.9% in 2021. It may therefore be worthwhile to have any dividend paid out before 2021, if this payment will be used for spending or to pay off an excessive loan from your company. If you will not be using the dividend for one of these purposes, it will form part of your private assets and will be taxed in box 3. Whether this option is attractive depends, amongst other things, on whether you have savings or investments in box 3, what return is achieved and how much tax you are paying on it.
From 1 January 2021 young people between the ages of 18 and 34 will be exempt from transfer tax when buying their own home. As of 1 April 2021 this exemption will only apply to homes with a value up to € 400,000. This is a one-off exemption, which means that if young persons within this category have already bought a home, they will still be entitled to the exemption if they buy another home. After all, they will not have previously made use of the exemption. One condition here is that they will live in the home themselves as their main place of residence. The exemption will result in a 2% saving in transfer tax.
If you are an entrepreneur and are planning to buy an electric car in the near future, it is advisable to do so before the end of 2020. That is because, from 2021, the 8% addition to taxable income for electric cars will be increasing to 12%. Furthermore, this 12% addition will apply only to the first € 40,000 of the list price instead of the first € 45,000, as is currently the case. A rate of 22% will be payable on the excess amount. The lower rate of the addition will apply for a period of 60 months from the date on which the vehicle first enters use.
As a director/major shareholder (DGA), you are entitled to deduct expense allowances from your customary salary. It makes no difference whether these expense allowances are taxed or untaxed. The addition to taxable income for private use of a company car also counts towards your customary salary. In the case of a car costing € 60,000 and an addition to taxable income of 22%, for example, you can therefore reduce your customary salary by € 13,200. As a DGA, reducing your customary salary means you will pay less tax in box 1.
If you make investments, in principle you are entitled to the small projects investment allowance (KIA). Planning your investments and, where possible, spreading them out is often worth the effort. For example, investing € 50,000 in 2020 and 2021 results in a KIA of € 28,000, while investing € 100,000 in 2020 and € 0 in 2021 entitles you to a KIA of just € 16,307. It is therefore worth getting the right advice if you want to take advantage of the KIA.
This year you can once again take advantage of the exemptions from gift tax. In 2020 you can make a tax-free gift of € 5,515 to your children and of € 2,208 to your grandchildren or third parties. For children between the ages of 18 and 40 this amount has also been increased this year on a one-off basis to:
The one-off donation of € 103,643 to buy a home also applies to persons other than your own children. If you make a gift in 2020, your assets in box 3 will fall, which can result in tax savings for you.
Please note: As a result of the coronavirus crisis, both the exemption for children and the exemption for grandchildren and third parties will be subject to a one-off increase of € 1,000 in 2021. The exemption will therefore amount to € 6,604 for gifts to children and € 3,244 for gifts to grandchildren and third parties in 2021. This increase will be reversed in 2022.
It has been an extraordinary year. As an entrepreneur, there is a good chance that this year, more than ever before, you could benefit from some useful tax-related and other year-end tips. We have picked out ten for you here.
READ
The fixed budget under the work-related expenses scheme (WKR) has been expanded this year. Up to a wage bill of € 400,000 the fixed budget amounts to 3%, with 1.2% applying to the excess amount. Assess the fixed budget you have remaining and make full use of it. Be sure to take advantage of the cost-efficiency threshold of € 2,400 per person per year. Up to this amount the Tax and Customs Administration will regard any allowances and benefits in kind granted as customary allowances and benefits. Only make use of the group scheme under the work-related expenses scheme if this will work out in your favor. As the fixed budget has been increased, this is less often the case than it was last year.
If your companies currently form part of a tax group, it may be beneficial to disband it. The tax group pays corporation tax on the combined profits of all the companies. In view of the increasing gap between the lower and higher rates of corporation tax, disbanding a tax group is becoming a more attractive option. From 2021, after all, there will be a difference of 10 percentage points between the rate in the first band and the higher rate (15% and 25% respectively). The lower rate will apply to the first € 245,000 of profits from 2021 and even to the first € 395,000 of profits from 2022.
If you purchase a commercial property, this year you will owe transfer tax at a rate of 6%. This rate will increase to 8% from 2021. We therefore recommended that, if possible, you complete a planned purchase of a commercial property before 2021.
As an entrepreneur, you are best off waiting until after 31 December to transfer liquid assets that generate low returns, such as cash in your business bank account, to your private assets. In this way you will avoid the relatively high tax in box 3. Conversely, it makes sense to transfer any necessary cash from your private assets to your business account before 31 December this year.
As a private individual, you can avoid the high rate of tax that applies in box 3, in particular to savings, by setting up a ‘savings company’ (‘spaar-bv’) or a mutual fund. You will then pay around 38% tax on the return actually received up to € 245,000. This is considerably less than the 0.59% to 1.76% tax that you will pay on your savings balances in box 3 in 2021, although you need to bear in mind that the exempted income in box 3 is being increased to € 50,000 per person in 2021.
The rate of tax on substantial shareholdings (box 2) will be increasing from 26.25% to 26.9% in 2021. It may therefore be worthwhile to have any dividend paid out before 2021, if this payment will be used for spending or to pay off an excessive loan from your company. If you will not be using the dividend for one of these purposes, it will form part of your private assets and will be taxed in box 3. Whether this option is attractive depends, amongst other things, on whether you have savings or investments in box 3, what return is achieved and how much tax you are paying on it.
From 2021 young people between the ages of 18 and 34 will be exempt from transfer tax when buying their own home. This exemption can be applied once, which means that if they already own their own home, they will still be entitled to the exemption if they buy another home, as they will not have previously made use of it. One condition here is that they will live in the home themselves as their main place of residence. The exemption will result in a 2% saving in transfer tax.
If you are an entrepreneur and are planning to buy an electric car in the near future, it is advisable to do so before the end of 2020. That is because, from 2021, the 8% addition to taxable income for electric cars will be increasing to 12%. Furthermore, this 12% addition will apply only to the first € 40,000 of the list price instead of the first € 45,000, as is currently the case. A rate of 22% will be payable on the excess amount. The lower rate of the addition will apply for a period of 60 months from the date on which the vehicle first enters use.
As a director/major shareholder (DGA), you are entitled to deduct expense allowances from your customary salary. It makes no difference whether these expense allowances are taxed or untaxed. The addition to taxable income for private use of a company car also counts towards your customary salary. In the case of a car costing € 60,000 and an addition to taxable income of 22%, for example, you can therefore reduce your customary salary by € 13,200. As a DGA, reducing your customary salary means you will pay less tax in box 1.
If you make investments, in principle you are entitled to the small projects investment allowance (KIA). Planning your investments and, where possible, spreading them out is often worth the effort. For example, investing € 50,000 in 2020 and 2021 results in a KIA of € 28,000, while investing € 100,000 in 2020 and € 0 in 2021 entitles you to a KIA of just € 16,307. It is therefore worth getting the right advice if you want to take advantage of the KIA.
This year you can once again take advantage of the exemptions from gift tax. In 2020 you can make a tax-free gift of € 5,515 to your children and of € 2,208 to your grandchildren or third parties. For children between the ages of 18 and 40 this amount has also been increased this year on a one-off basis to:
The one-off donation of € 103,643 to buy a home also applies to persons other than your own children. If you make a gift in 2020, your assets in box 3 will fall, which can result in tax savings for you.
It has been an extraordinary year. As an entrepreneur, there is a good chance that this year, more than ever before, you could benefit from some useful tax-related and other year-end tips. We have picked out ten for you here.
READ
Netherlands - United Kingdom
According to the general rule, after a no-deal Brexit a service provided to a VAT-registered business in the United Kingdom will be taxed in the customer’s country: the United Kingdom. The VAT-registered seller does not include any VAT on the invoice and instead states 'VAT Out of Scope'. This turnover is not entered on the VAT return.
United Kingdom - Netherlands
After a no-deal Brexit, services that a Dutch VAT-registered business has purchased from a VAT-registered business in the United Kingdom will be taxed in the Netherlands and entered under questions 4b and 5b of the VAT return, unless an exception applies to the service in question.
Netherlands - United Kingdom
After a no-deal Brexit, goods supplied to a customer in the United Kingdom will be regarded as an export and the VAT will be zero-rated. An export declaration will have to be submitted to the Dutch customs authorities and this turnover will be entered under question 3a of the VAT return. The VAT-registered business will have to retain the customs documents in its records to substantiate the zero rate of VAT.
An import declaration will also have to be submitted in the United Kingdom. Some Dutch VAT-registered businesses do not want to burden their customers in the United Kingdom with import formalities and are planning to take care of these formalities themselves. That means these businesses will need to apply for a British VAT number, pay import VAT and charge British VAT.
From 2021 the United Kingdom is introducing a scheme under which import VAT will not have to be paid in the UK at the same time as the goods are imported. The VAT will be declared and recovered on the same VAT return. This scheme will apply to all VAT-registered businesses in the UK. Dutch VAT-registered businesses that wish to do business in this way are advised to register soon, as there is currently a long processing time for registrations.
United Kingdom - Netherlands
After a no-deal Brexit, a Dutch VAT-registered business that buys goods from the United Kingdom and imports them will have to submit an import declaration to the Dutch customs authorities, pay import duties and VAT on the import to the customs authorities and then claim back this VAT on its VAT return under question 5b, unless it holds an Article 23 permit.
A VAT-registered business that applies for an Article 23 permit can enter the VAT owed on imported goods on its VAT return under question 4a instead of having to pay the VAT immediately at the time of import. The import VAT can be claimed back under question 5b of the VAT return. It is possible to apply for the Article 23 permit if the relevant requirements are met:
According to the general rule, a service provided by a Dutch VAT-registered business to a consumer in the United Kingdom is taxed in the Netherlands. After a no-deal Brexit, the Dutch VAT-registered business will have to charge 21% or 9% VAT and enter this under section 1a or 1b of its VAT return.
Sales of goods by a Dutch VAT-registered business to consumers will be regarded as exports and no VAT will be owed in the Netherlands. The Dutch VAT-registered business will enter this under section 3a of its VAT return.
Dutch VAT-registered businesses that are entitled to a refund of VAT paid in 2020 in the United Kingdom can claim this in the usual way via the portal of the Dutch Tax and Customs Administration. It is important that VAT paid in 2020 in the United Kingdom is claimed back before 1 January 2021.
A Dutch VAT-registered business requires an EORI number to do business with VAT-registered businesses outside the EU. It is a good idea for a VAT-registered business to check what its EORI number is now, or apply for one if necessary, to avoid any trading difficulties after 1 January 2021.
If you are a Dutch VAT-registered business, apply for an Article 23 permit via the website of the Dutch Tax and Customs Administration if you do not yet have one.
Please note: Brexit is and will remain the subject of much uncertainty, but it is important to make preparations in good time as 1 January 2021 draws ever closer.
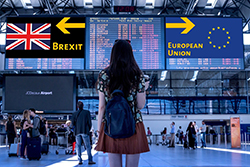
The Brexit negotiations are proving difficult. As a result, the risk of a no-deal Brexit (the United Kingdom leaving the EU without any trade agreements) is becoming ever more likely. What will a no-deal Brexit mean for VAT-registered businesses and how can they prepare for it?
READ
Nederland - Verenigd Koninkrijk
Een dienst verricht aan een btw-ondernemer in het Verenigd Koninkrijk is volgens de hoofdregel na een harde Brexit belast in het land van de afnemer, het Verenigd Koninkrijk. De btw-ondernemer vermeldt geen btw op de factuur maar de woorden 'VAT Out of Scope'. Deze omzet komt niet in de btw-aangifte.
Verenigd Koninkrijk - Nederland
Diensten die door een Nederlandse btw-ondernemer zijn afgenomen van een btw-ondernemer in het Verenigd Koninkrijk, zijn na een harde Brexit belast in Nederland en aan te geven bij vraag 4b en 5b van de btw-aangifte, tenzij het gaat om een dienst waarvoor een uitzondering geldt.
Nederland - Verenigd Koninkrijk
Een levering van goederen aan een afnemer in het Verenigd Koninkrijk is na een harde Brexit export en wordt met 0% btw belast. Er moet aangifte ten uitvoer worden gedaan bij de Nederlandse Douane en deze omzet wordt aangegeven bij vraag 3a in de btw-aangifte. De btw-ondernemer moet de douanedocumenten bewaren in zijn administratie om het btw-tarief van 0% te onderbouwen.
Tevens moet er invoeraangifte worden gedaan in het Verenigd Koninkrijk. Er zijn Nederlandse btw-ondernemers die hun klanten in het Verenigd Koninkrijk niet willen opzadelen met invoerformaliteiten en gaan de formaliteiten zelf verzorgen. Dit heeft tot gevolg dat deze btw-ondernemers een Engels btw-nummer moeten aanvragen, btw bij invoer moeten betalen en Engelse VAT in rekening moeten brengen.
Het Verenigd Koninkrijk gaat vanaf 2021 een regeling invoeren, zodat in het VK de btw bij invoer niet op hetzelfde moment als de invoer hoeft te worden betaald. De btw wordt betaald op de btw-aangifte en in dezelfde aangifte in aftrek gebracht. Deze regeling geldt voor alle btw-geregistreerde ondernemers in het VK. Het is raadzaam dat een Nederlandse btw-ondernemer die op deze wijze zaken wil doen, zich snel registreert omdat de doorlooptijd van de registratie op dit moment lang is.
Verenigd Koninkrijk - Nederland
Een Nederlandse btw-ondernemer die goederen in het Verenigde Koninkrijk koopt en importeert, moet na een harde Brexit bij de Nederlandse Douane een aangifte ten invoer indienen, invoerrechten betalen en btw over de invoer bij de Douane betalen om die vervolgens terug te vragen op de btw-aangifte bij vraag 5b, tenzij hij over een artikel 23-vergunning beschikt.
Een btw-ondernemer die een artikel 23-vergunning aanvraagt, mag de btw bij invoer van goederen aangeven in de btw-aangifte bij vraag 4a, in plaats van dat de btw direct bij invoer verschuldigd is. De btw over de invoer kan worden teruggevraagd bij vraag 5b van de btw-aangifte. De artikel 23-vergunning kan worden aangevraagd als aan de eisen daarvoor wordt voldaan:
Een dienst verricht aan een consument in het Verenigd Koninkrijk door een btw-ondernemer in Nederland is, volgens de hoofdregel, belast in Nederland. De Nederlandse btw-ondernemer moet na een harde Brexit 21% of 9% btw in rekening brengen en dit aangeven in zijn btw-aangifte bij rubriek 1a of 1b.
Bij verkoop van goederen door een btw-ondernemer in Nederland aan consumenten is sprake van export en is 0% btw in Nederland verschuldigd. De btw-ondernemer in Nederland geeft dit aan in rubriek 3a van zijn btw-aangifte.
Nederlandse btw-ondernemers die recht hebben op btw-teruggave van de in 2020 in het Verenigd Koninkrijk betaalde btw, kunnen dit op de gebruikelijke manier via de portal van de Nederlandse Belastingdienst doen. Het is van belang dat de in 2020 in het Verenigd Koninkrijk betaalde btw vóór 1 januari 2021 teruggevraagd wordt.
Een Nederlandse btw-ondernemer heeft een EORI-nummer nodig om zaken te doen met btw-ondernemers buiten de EU. Een btw-ondernemer doet er verstandig aan om alvast na te gaan wat zijn EORI-nummer is of, indien nodig, aanvraagt zodat er geen handelsproblemen ontstaan na 1 januari 2021.
Vraag als Nederlandse btw-ondernemer een artikel 23-vergunning aan via de website van de Nederlandse Belastingdienst als u deze vergunning nog niet heeft.
Let op! De Brexit is en blijft een onzekere aangelegenheid maar een tijdige voorbereiding is van belang nu 1 januari 2021 steeds dichterbij komt.
De onderhandelingen omtrent de Brexit verlopen moeilijk, waardoor de kans op een harde Brexit, het uittreden van het Verenigd Koninkrijk zonder handelsakkoorden, steeds reëler lijkt te worden. Wat betekent een harde Brexit voor btw-ondernemers en op welke manier kunnen zij zich hierop voorbereiden?
READ
To make it easier for first-time buyers to access the housing market, an exemption from transfer tax will be introduced from 1 January 2021. This exemption will apply to buyers aged between 18 and 35 who are purchasing their own home. If the buyer has already benefited from the transfer-tax exemption or is 35 years of age or older, the current rate of 2% will apply to the purchase.
The rate of transfer tax applicable to property purchased by investors and legal entities, as well as to homes that are not used as a main residence, will increase to 8% (6% in 2020).
From 1 January 2021 the tax allowance will be increased to € 50,000 per taxpayer. This means savers and small investors with assets of up to € 50,000 (or € 100,000 if they have a tax partner) will no longer pay tax on these assets. Anyone with assets of € 50,000 or more in 2021 will pay 31% tax on the income from these assets from 2021 onwards. A rate of 30% currently applies in 2020.
Please note the asset threshold used to determine whether a person is entitled to allowances will be € 31,430!
In 2021 the rate of income tax in the first band (taxable income up to and including € 68,507) will be reduced from 37.35% to 37.10%. From 2022 to 2024 the government will lower this rate further to 37.03%. The rate of income tax in the second band (taxable income from € 68,507) will remain at 49.5%.
To reduce the difference in the tax burden borne by employees and self-employed people, the self-employed person’s allowance will be cut at a faster rate. It will ultimately reach a level of € 3,240 in 2036. The maximum self-employed person’s allowance for 2021 will be € 6,670.
An increase in the employed person’s tax credit from € 3,819 to € 4,205 in 2021 and the cutting of the basic rate of income tax to 37.10% will compensate entrepreneurs for this reduction in the self-employed person’s allowance.
The lower rate of corporation tax will be cut from 16.5% to 15%. With effect from 2021 this lower rate will apply to profits of up to € 245,000 instead of € 200,000. This threshold will be raised further to € 395,000 in 2022. The higher rate of corporation tax will remain at 25%.
One of the coronavirus support measures that has been introduced is an increase in the fixed budget under the work-related expenses scheme from 1.7% to 3% on the first € 400,000 of the taxable wage bill. This will apply in 2020 only.
From 1 January 2021 the calculation of the fixed budget will be restricted again: up to a taxable wage bill of € 400,000 a rate of 1.7% will apply, with a rate of 1.18% (2020: 1.2%) applicable above € 400,000.
Last year it was announced that the addition to taxable income for the private use of electric cars would be increased incrementally. With effect from 1 January 2021 the addition to taxable income for the private use of electric cars will be 12% (2020: 8%) on a maximum of € 40,000 (2020: € 45,000). Is the list price more than € 40,000? In that case the normal addition of 22% will apply on the amount above this figure.
Over the coming years the addition will be increased further, rising to 16% in 2022 and 17% in 2025. The maximum list price up to which the lower addition is applicable will not be raised and will remain at € 40,000. One new regulation being introduced from 1 January 2021 is that the maximum list price will not apply to solar cars powered by integrated solar panels. The government’s intention here is to anticipate developments on the automotive market.
It is possible that jobs will be lost as a result of the coronavirus crisis. The government is keen to give anyone who finds themselves in this position greater opportunities to retrain. From 2021 employers will therefore also be able to reimburse the training costs of former employees free of tax.
The details of the scheme are yet to be worked out, but to stimulate investment a new investment tax credit will be introduced, which entrepreneurs can offset against their payroll taxes.
At present, many companies generate profits in the Netherlands, but do not pay any tax, as a result of offsetting losses or certain deductible items. The following measures have been announced to prevent this:
What proposals and changes in the area of taxation did Dutch Minister of Finance Wopke Hoekstra pull from his briefcase on the third Tuesday of September? The measures set out in the 2021 Tax Plan have been influenced greatly by the coronavirus crisis. A brief explanation of the ten most important proposals and changes is provided below.
READ
Code yellow countries are countries that have more or less the same infection risks as the Netherlands. The local rules for keeping sufficient distance, hand hygiene and wearing face masks are also similar to those in the Netherlands. Code yellow countries for instance are Germany, France and Italy.
If an employee falls ill during a stay in a code yellow country - it does not matter whether he has simply fallen ill or has contracted corona - he will report sick and is then on sick leave, in which case the employer has an obligation to continue paying his wages.
The Government will no longer repatriate people from a code yellow country who have contracted corona. If someone takes the risk of going to a code yellow country, this is his own risk. It is also important to check the policy conditions of the health care insurance to see what will be reimbursed.
Code orange countries themselves indicate that Dutch tourists are not welcome (yet), or the Dutch government indicates that the risk of infection with the coronavirus in that country is even higher than in the Netherlands. Holiday trips to code orange countries are therefore not advised against.
The Dutch Government does not help with repatriation from a code orange country either. But travel organizations have to repatriate travellers who have booked a package holiday with them. This means that in the situation where the country in question goes from code yellow to code orange, people will be repatriated, but this only applies for travellers with package holidays from travel organizations. So not in case of self-booked trips.
If an employee goes to a code orange country, the Government urgently advises to go in quarantine for two weeks immediately upon arrival back in the Netherlands. An employee who consciously chooses to go on holiday to a code orange country therefore knows that he will have to go in quarantine after his return. If he can work from home, this is not a problem. If he cannot work from home, he therefore cannot work. Because he knows this in advance, the employee may take the position that the cause that the employee does not perform his work lies in his own sphere of risk. This may mean that the relevant employee is not entitled to continued payment of salary during the period that he is in quarantine. Another option is that the employee takes days off during the quarantine period.
If a country goes from code yellow to code orange during the holiday, as a result of which the employee has to go in quarantine during the holiday or after his return, this in principle is not in the employee's sphere of risk. This may be different if there were signals beforehand that the country's code might change from yellow to orange.
Tip! Inform your employees in writing in advance of the consequences if they go on holiday to a code orange country and then have to be quarantined. This way, the employee knows in advance where he stands, and can adjust his choices and actions accordingly.
Attention! As with the code yellow countries, if the employee contracts corona or otherwise falls ill during his holiday, you as his employer must continue paying his wages.
Since 1 January 2020, the main rule in Dutch law has changed from 'no labour, no wage' to 'no labour, but wage payment continues'. The latter is only different if the cause for the non-performance of the work is at the risk and expense of the employee. The burden of proof for this lies with the employer.
Code red countries are almost completely closed to travellers. Travelling to such countries is seriously advised against, because 'life-threatening situations may arise', for example because the country is at war. Your employee will not go on holiday there.
Tip! Do you want to know which countries are yellow, orange or red? Then visit the website “Netherlands Worldwide”, a website of the Dutch Government.
The holiday season is approaching again. Is your employee going on holiday to a country with code yellow as travel advisory? What are the consequences if this employee falls ill or has to be quarantined during the holiday?
READ
There will now be more compensation available for fixed costs, the redundancy penalty under the Temporary Emergency Bridging Fund for Employment (NOW scheme) will be removed and seasonal businesses will be offered a helping hand. In addition, a partner test will be introduced under the Temporary Bridging Scheme for Independent Entrepreneurs (Tozo).
The contribution towards payroll costs that can be obtained under the NOW scheme will continue to apply from June to August for companies that suffer a drop in turnover of at least 20%. One important expansion being introduced via NOW 2.0 is that entrepreneurs will now receive a mark-up of 40% instead of the current 30% on their payroll costs.
Under the new scheme it is permitted to make employees redundant for commercial reasons without incurring a 50% penalty on the contribution received. Compensation for seasonal businesses also forms part of the new scheme.
Please note: To qualify for the new NOW, companies are prohibited from distributing dividends, paying bonuses to their management and board or buying back their own shares this year.
To date, under the Contribution for Entrepreneurs in Sectors Affected by COVID-19 scheme (TOGS) it has been possible for companies to obtain fixed compensation of € 4,000 for fixed costs. Under a new scheme compensation for fixed costs will now be available up to a maximum level of € 20,000 for the period from June to August. This applies if a company has suffered a drop in turnover of at least 30%.
Please note: The amount of compensation that an entrepreneur can receive on balance depends on the size of the company, the level of its fixed costs and the drop in turnover suffered.
The Temporary Bridging Scheme for Independent Entrepreneurs (Tozo) is also being extended. Under this scheme independent entrepreneurs who are experiencing financial difficulties can apply for additional assistance to supplement their income up to the level of the minimum social income. The new Tozo will, however, include a partner test. To date, any income of a partner has not been counted when determining the level of the contribution, but this will now be taken into account under the new scheme.
The period during which affected entrepreneurs can apply for a deferment of tax payments has been extended until 1 September 2020. Any default penalties for late payment do not have to be paid. The rates of tax interest and late payment interest have been reduced to 0.01% until 1 October 2020 for all types of tax.
In addition, the other tax measures introduced, namely the relaxation of the hour criterion for self-employed persons, the mortgage payment holiday, the VAT exemption for medical aids and the VAT exemption for the loaning out of healthcare personnel, are being extended until 1 September 2020.
Entrepreneurs will be immediately granted a three-month deferment of payments on submission of their first application. An application only needs to be submitted once for this three-month period.
Please note: Entrepreneurs who apply for a deferment of more than three months may not pay out any dividends or bonuses or buy back their own shares.
A deferment granted for more than three months will last until the deferment is withdrawn, which will not be before 1 September 2020. Upon expiry of the deferment entrepreneurs will be offered an appropriate payment arrangement. What this payment arrangement will involve is not yet clear.
The additional, expanded or more accessible loans and guarantees that were available to small and medium-sized enterprises, start-ups and scale-ups under the first emergency package will continue. This relates to the coronavirus modules of the government-guaranteed scheme for loans to SMEs (BMKB) and Corporate Finance Guarantee Scheme (GO), the new Small Loans Coronavirus Guarantee Scheme (KKC) and the increased budget for the SEED Capital scheme.
The Coronavirus Bridging Loan (COL), which helps to improve the liquidity position of innovative companies (start-ups and scale-ups), will be allocated an additional € 150 million over the next three months due to the large number of applications received.
The second support package intended to help entrepreneurs deal with the coronavirus crisis was announced by the Dutch Government on Wednesday, 20 May. This largely extends the measures for a further three months (from June to August). What changes will the new package introduce?
READ
The NOW scheme reimburses up to 90% of the payroll costs of companies whose turnover drops by at least 20%. The drop in turnover is determined by taking 25% of the turnover for 2019 as a reference. This has to be compared with the turnover generated from March to May 2020. However, employers can also take a period starting one or two months later as a basis.
One of the changes concerns the requirement that a company applying under the NOW must have a Dutch bank account number. This requirement will no longer apply, as it is sometimes causing significant difficulties in practice. Employers who have a SEPA bank account number from outside the Netherlands therefore no longer need to provide a Dutch bank account number.
Applicants under the NOW also automatically agree to the possible publication of data relating to the NOW application under the Government Information (Public Access) Act (WOB). However, within the context of the subsidy application certain information to which the Employee Insurance Agency (UWV) has access may be competitively sensitive. For this reason it has been decided that the automatic agreement will only apply to a number of items of data that are the most relevant for ensuring transparency of public spending, but do not reveal any business secrets.
It has been clarified that an intra-group secondment operating company (‘personeels-bv’) within a group cannot take advantage of the NOW scheme itself. However, this option is available to other companies within the group.
Employers who apply to the NOW scheme and are also entitled to the wage expenses subsidy (LKS) for employees with an occupational disability do not need to deduct this subsidy from the amount awarded under the NOW. Consequently, there is no longer any need to notify the local authority of the allocation of the NOW subsidy.
Please note: The turnover threshold above which a declaration from an accountant will be required is not yet known.
A number of further changes have been made to the NOW scheme. These relate to foreign bank account numbers, the publication of data, clarification of the situation that applies to intra-group secondment operating companies and notification of the wage expenses subsidy.
READ
The obligation to report applies to foreign employers and self-employed professionals from the European Union, other countries in the European Economic Area (EEA), or Switzerland.
You will have to report any new services from 1 March 2020 onwards. However, any services that start on or after 1 March can already be reported with effect from 10 February 2020.
If you are a service provider or self-employed professional working in the road freight transport sector (SBI H 49.4 according to the Dutch Chamber of Commerce) or if you provide services on the instructions of a company established in the Netherlands, you can report annually. You only need to report once a year then.
A special website is available for reporting. You have to report digitally, e.g. by means of eHerkenning (an initiative of the Dutch government to enable safe login).
Please note! The obligation to report does not apply to passenger transport or to transport by water.
If you have any questions about the obligation to report, please contact us.
With effect from 1 March 2020, foreign carriers transporting goods in the Netherlands will be under the obligation to report these activities, unless they only transport the goods through the Netherlands, without loading or unloading.
READ

Weert branch
Schoutlaan 7
6002 EA Weert
0495 53 07 55
info@w-o.nl
W&O Accountants en Adviseurs
General terms and conditions
Complaints procedure
Whistleblower policy
Privacy statement
